
Blogs
PW Consulting: Niraparib Market Hits $1.18B in 2025, Set for $2.68B by 2032 at 12.43% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Phase of Niraparib Growth: Strategic Intelligence for 2026 Decision-Makers
The Imperative for Precision Intelligence in Oncology Markets
The global landscape for poly (ADP-ribose) polymerase (PARP) inhibitors has entered a mature yet dynamically expanding phase, where competitive differentiation is increasingly defined by indication expansion, partnership structuring, and regulatory agility. As pharmaceutical leaders, investors, and market access strategists plan their portfolios for 2026, relying on fragmented secondary sources or legacy projections introduces significant strategic risk. This is precisely the gap our newly released Worldwide Niraparib Market research report is engineered to close. Designed as a decision-grade intelligence asset, the study translates multi-year epidemiological shifts, commercialization trajectories, and regulatory milestones into an actionable roadmap for enterprise planning.
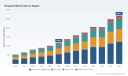
Drawing on historical performance data spanning 2020 through 2025 and forward-looking projections through 2032, the report captures a market that has demonstrated remarkable compounding momentum. In 2020, global niraparib revenues stood at approximately $520.4 million, accelerating to $1.18 billion by 2025, with the trajectory projected to reach roughly $2.68 billion by 2032. This expansion reflects a compound annual growth rate of 12.43 percent, a figure that signals sustained commercial viability rather than transient momentum. For executives evaluating capital allocation, pipeline prioritization, or market entry timing, these macro indicators establish a foundational baseline. However, the true strategic value lies beyond the headline numbers. Our analysis isolates the structural drivers behind this growth, mapping how indication breadth, regional commercialization architectures, and formulation dynamics interact to shape revenue realization across different business models.
The report will be distributed and consumed as a comprehensive reference tool for strategy, business development, and market access teams. Rather than treating niraparib as a single-product narrative, we frame it within a multi-actor ecosystem where originator rights, territory-specific licensing, API supply chains, and companion diagnostics converge to determine market access and pricing leverage. For organizations preparing for 2026 and beyond, the study offers the analytical rigor required to anticipate shifts in competitive positioning, regulatory pathways, and reimbursement environments before they materialize in quarterly earnings calls or competitor press releases.
Decoding the Commercial Architecture: Indication Expansion and Dosage Dynamics
Niraparib's commercial story has evolved from a focused maintenance therapy in advanced ovarian, fallopian tube, and primary peritoneal cancers into a broader oncology asset with expanding therapeutic relevance. Our segmentation analysis provides granular visibility into how revenues are distributed across clinical indications, enabling stakeholders to assess where commercial gravity is concentrated and where incremental growth vectors are emerging. Ovarian cancer remains the dominant indication, reflecting niraparib's established positioning in maintenance treatment paradigms. Prostate cancer represents a structurally distinct and rapidly evolving revenue stream, driven by targeted combinations and molecularly defined patient populations. Additional solid tumor applications contribute a more specialized but strategically important share, often serving as platforms for clinical expansion and label broadening.
Equally critical to commercial planning is the dosage form architecture. The market reflects a clear preference for capsule-based formulations, which currently capture the majority of realized revenue, while tablet formats represent a meaningful complementary segment. For manufacturers, distributors, and market access teams, understanding formulation-level consumption patterns is essential for supply chain forecasting, packaging strategy, and payer negotiations. These dynamics are not static; they respond to clinical convenience, adherence considerations, and regulatory label evolution. Our report details how dosage form preferences intersect with patient population characteristics and prescribing behavior, giving commercial leaders a clearer view of where operational adjustments can protect or expand market share.
Worldwide Imbruvica Market
Importantly, the analysis does not stop at static segmentation snapshots. The study tracks how indication momentum and formulation adoption interact over the forecast horizon, enabling scenario-based planning for teams evaluating market penetration timelines, regional launch sequencing, or partnership structuring. By connecting clinical positioning to commercial outcomes, the report equips decision-makers with a more precise lens for evaluating which growth drivers are structural and which are contingent on regulatory or reimbursement developments.
Worldwide Niraparib Market
Competitive Ecosystem and the Strategic Role of Partnerships
Niraparib's market structure is highly concentrated, with a small number of players controlling the majority of commercial rights and supply pathways. This concentration shapes pricing behavior, launch timing, and the competitive intensity of indication expansion. At the core of the ecosystem, GlaxoSmithKline operates as the originator and primary marketer of ZEJULA, holding global commercialization rights outside specific partnered territories following its acquisition of Tesaro. GSK's leadership position is reinforced by continuous label optimization and strategic regulatory engagement, including recent prescribing information updates that refine dosage and administration guidance for maintenance treatment in ovarian cancer. These updates demonstrate how originator companies can sustain commercial relevance by aligning label language with evolving clinical practice.
Janssen Biotech, a Johnson & Johnson company, represents a strategically distinct contributor, holding exclusive rights outside Japan to niraparib in prostate cancer. This focused indication portfolio has enabled Janssen to build a differentiated commercial narrative, most notably through AKEEGA, a dual-action tablet combining niraparib with abiraterone acetate. Recent regulatory activity underscores the acceleration of this prostate cancer strategy: the U.S. FDA granted Priority Review for a supplemental new drug application for AKEEGA in BRCA-mutated metastatic castration-sensitive prostate cancer, followed by approval for expanded use in BRCA2-mutated metastatic castration-sensitive prostate cancer with prednisone. These milestones do more than expand indication coverage; they signal a broader shift toward molecularly targeted combination regimens in prostate oncology, where niraparib is positioned as a critical component of combination-based treatment architecture.
The commercial architecture is further shaped by territory-specific partners who localize execution and navigate regulatory and reimbursement complexities. Zai Lab Limited operates as GSK's commercialization partner for niraparib in Greater China under a licensing agreement, providing localized market access and distribution capabilities. Takeda Pharmaceutical holds exclusive rights to develop and commercialize niraparib in Japan through a legacy TESARO licensing agreement, reflecting how regional rights structures can preserve long-term market participation even when global originator control is consolidated elsewhere. These partnership models are central to understanding how niraparib reaches distinct patient populations while navigating varying healthcare system requirements.
Below the branded commercial layer, a network of API manufacturers supports supply chain resilience and regional formulation capacity. Companies such as Biophore India Pharmaceuticals, TAPI Technology & API Services, Sichuan Qingmu Pharmaceutical, Anhui Provincial, and Dr. Reddy's Laboratories operate as active suppliers within the niraparib API ecosystem, each with differing capabilities and market presence. For stakeholders evaluating supply security, cost structures, or potential generic entry timelines, mapping these upstream participants is essential. The report provides a structured view of this supplier landscape, helping procurement, business development, and competitive intelligence teams distinguish between manufacturing capability and commercial market impact.
Regulatory Catalysts, Diagnostic Integration, and Reimbursement Intelligence
Market performance in oncology therapeutics is increasingly inseparable from regulatory timing, diagnostic availability, and access negotiations. Niraparib's recent trajectory illustrates how closely these forces interact. In March 2026, the FDA approved Myriad Genetics' MyChoice CDx test as a companion diagnostic for niraparib in HRD-positive advanced ovarian cancer patients. The approval of a companion diagnostic is not merely a clinical milestone; it defines the eligible patient universe, influences testing adoption pathways, and shapes the economics of prescriber behavior. For market access strategists, diagnostic integration introduces both opportunity and complexity, because reimbursement for testing can directly affect therapy uptake and treatment sequencing.
On the regulatory front, GSK's June 2025 label update for ZEJULA demonstrates how ongoing engagement with prescribing information can reinforce clinical clarity and support appropriate use. Meanwhile, Janssen's late-2025 regulatory activity surrounding AKEEGA reflects the growing importance of combination product pathways in competitive oncology markets. The approval of AKEEGA for BRCA2-mutated metastatic castration-sensitive prostate cancer under Priority Review, alongside the earlier Priority Review filing, indicates that regulators are actively creating pathways for molecularly defined prostate cancer populations. These developments matter for forecasting because indication approvals can restructure competitive positioning, expand addressable populations, and shift payer expectations around value demonstration.
Reimbursement and access dynamics add another layer of strategic complexity. GSK's reported global net revenues for ZEJULA in 2025 reached approximately $1.8 billion, a figure that highlights the commercial scale already achieved while also underscoring the importance of sustained access performance across major markets. At the same time, patent protection remains a central variable in long-term market planning. Core U.S. patents for ZEJULA extend to March 2038 for compositions and January 2039 for formulations, and as of April 2026, no generic versions have been approved. This patent posture influences the timing of competitive entry, the durability of pricing power, and the strategic calculus for both originator teams and potential market entrants.
Our report integrates these regulatory, diagnostic, and access variables into a cohesive view of market dynamics. Instead of treating them as isolated news items, the analysis maps how they compound over time, affecting launch sequencing, patient identification, reimbursement negotiations, and competitive response. For organizations building 2026 plans, this integrated perspective reduces uncertainty and supports more resilient assumptions about uptake curves, pricing environments, and competitive pressure points.
Strategic Takeaways for 2026 and Beyond
For executives and analysts operating in the niraparib space, the 2026 planning environment demands more than aggregate market size estimates. It requires a clear understanding of how indication strategy, territory partnerships, dosage form dynamics, API supply structures, and regulatory momentum intersect to create competitive advantage. The Worldwide Niraparib Market research report is designed to deliver that integrated view. By combining historical performance through 2025 with a detailed forecast horizon through 2032, the study enables stakeholders to stress-test commercial assumptions, evaluate partnership opportunities, and anticipate the strategic implications of regulatory and diagnostic developments.
Several themes stand out as especially relevant for decision-makers. First, the market's 12.43 percent CAGR through 2032 reflects durable demand expansion, but that expansion is unevenly distributed across indications, formulations, and geographies. Second, competitive concentration remains high, meaning that strategic moves by GSK and Janssen can have outsized effects on pricing, launch timing, and indication competition. Third, partnership architectures in China and Japan illustrate how localized execution can sustain market participation in complex healthcare environments. Fourth, the companion diagnostic approval and evolving prostate cancer combination strategy demonstrate that future growth will increasingly depend on molecular targeting and access to defined patient populations.
To fully act on these insights, stakeholders need the deeper segmentation detail, company-level profiles, and scenario-ready forecasts contained in the complete report. The publication goes beyond the headline trajectory to provide the operational intelligence required for concrete planning: regional commercialization pathways, indication-level revenue architecture, dosage form consumption context, competitor positioning, and the evolving regulatory and reimbursement landscape. For organizations that need to convert market visibility into executable strategy, this research offers a structured foundation for confident decision-making.
The full report is available now for teams preparing their 2026 strategic plans. Accessing the complete analysis will provide the comprehensive segmentation breakdowns, competitor profiles, and forward-looking scenario data necessary to move from broad market awareness to precise commercial execution.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Load Control Market to Hit $275M by 2032, 6.72% CAGR
By pmarketresearch, 2026-09-16
Navigating Precision: Strategic Insights into the Worldwide Aircraft Load Control Solution Market
The aviation industry stands at a critical juncture where operational efficiency and safety compliance are no longer mutually exclusive goals but intertwined necessities. As aircraft operations become increasingly complex and fuel costs continue to exert pressure on airline margins, the role of precise load control has evolved from a regulatory checkbox to a strategic asset. PW Consulting is proud to introduce our latest comprehensive market research, Worldwide Aircraft Load Control Solution Market, designed to equip industry leaders with the intelligence needed to navigate the forecast period of 2026 to 2032.
This report is not merely a collection of statistics; it is a strategic roadmap derived from rigorous analysis of historical performance and future projections. Based on a base year of 2025 and historical data spanning from 2020 to 2025, our forecast indicates a robust trajectory for the sector. The global market, valued at approximately 174.45 million USD in 2025, is projected to reach around 275.03 million USD by 2032. This growth represents a Compound Annual Growth Rate (CAGR) of 6.72 percent over the forecast period. Such expansion signals a shift in how airlines and ground handlers view weight and balance systems, moving from legacy on-premise setups toward more agile, integrated digital ecosystems.
Macroeconomic Drivers and Market Trajectory
The steady climb in revenue from 122.45 million USD in 2020 to the projected 2032 figures reflects more than just inflation or fleet expansion. It underscores a fundamental transformation in aviation operations. The post-pandemic recovery phase saw a resurgence in passenger demand, but the underlying driver for load control solutions is the increasing need for automation and data accuracy. As aircraft become heavier and routes more varied, the margin for error in weight distribution narrows. Regulatory bodies globally are tightening compliance requirements, necessitating solutions that minimize human error and provide real-time verification.
Our analysis suggests that the growth rate will be sustained by the dual pressures of safety mandates and cost optimization. Fuel burn is directly correlated to aircraft weight and center of gravity positioning. Solutions that enable precise loading calculations contribute directly to fuel savings, offering a clear ROI for airlines operating on thin margins. Furthermore, the integration of load control with flight planning and dispatch systems is becoming a standard expectation rather than a premium feature. This holistic approach to operations is driving the demand for sophisticated digital load monitoring technologies, aligning with broader industry initiatives like the FAA's NextGen implementation program which emphasizes data-driven decision-making in aircraft operations.
Solution Ecosystems: Cloud, On-Premise, and Deployment Models
When examining the solution landscape, the market is broadly categorized by deployment architecture and the nature of services provided. The industry is witnessing a gradual shift in preference regarding where these critical calculations reside. While traditional on-premise solutions have long been the standard for stability and security, the agility offered by cloud-based architectures is gaining traction, particularly among carriers looking for scalability and remote access capabilities. Our research delves into the revenue contributions of each model, analyzing how different carrier sizes and operational models influence their choice of deployment.
Similarly, the end-user landscape is diverse, encompassing passenger airlines, cargo airlines, and ground handling companies. Each segment faces unique challenges. Passenger airlines must balance baggage, cargo, and passenger distribution to maintain trim and safety, while cargo operators focus on maximizing payload within structural limits. Ground handling companies, often acting as service providers for multiple carriers, require systems that can adapt to varying airline protocols quickly. The report provides a detailed breakdown of how these end users are adopting specific technologies, highlighting the distinct value propositions that resonate with each group. For instance, centralized load control services are becoming increasingly popular among handlers seeking to standardize operations across multiple stations.
Competitive Landscape: Established Giants and Specialized Innovators
The market structure is characterized by a mix of large aerospace conglomerates, IT giants, and specialized niche players. Our concentration analysis indicates a moderately consolidated environment, with the top three companies holding a significant share of the market, while the top five extend this influence further. This concentration suggests that while there is room for innovation, scale and integration capabilities remain key differentiators.
Among the key players, Jeppesen, a Boeing company, continues to leverage its heritage with modules like Powerloader and eLoadsheet, integrating tightly with flight planning and dispatch workflows. Their presence underscores the importance of ecosystem integration, where load control is not a siloed function but part of a broader airline operations suite. Similarly, Amadeus IT Group and Sabre Corporation offer load control functionalities within their expansive airline IT ecosystems, providing seamless data flow between reservation, departure control, and load management systems.
On the specialized front, companies like Damarel Systems International Ltd. offer focused solutions such as LodeStone, catering specifically to narrow and wide-body commercial aircraft with an emphasis on central load control and station operations. Evionica distinguishes itself with smart Weight and Balance solutions that emphasize automation, claiming over 80 percent autonomous loadsheet generation, which appeals to airlines seeking to reduce manual workload. Smart4Aviation Technologies B.V. provides a visual exception-based approach with S4A Smart LOAD, monitoring the full loading process and supporting both centralized and decentralized models.
Other notable participants include ABOMIS Innovations, which focuses on optimized load allocation and real-time calculations, and AeroData, known for integrating weight and balance tools with performance platforms to maximize load capacity. Regional players like A-ICE in Italy and Air Dispatch in the Czech Republic contribute to the diversity of the market, offering tailored systems for specific operational contexts. In the service domain, Swissport International AG operates Central Load Control centers, recently highlighting operations in Morocco and Kenya supporting over 50 airlines and processing significant volumes of load sheets annually. This service-oriented approach is complemented by firms like Samsic Assistance Aviation and Global Load Control, which provide remote aviation load control services to enhance safety and fuel efficiency through accurate weight distribution.
Regulatory Dynamics and Operational Imperatives
Compliance is the bedrock upon which the load control market rests. Stringent aviation safety regulations from authorities like ICAO and FAA mandate precise weight and balance calculations. The consequence of non-compliance is not merely financial but existential, involving safety risks and regulatory sanctions. Consequently, solutions are required to minimize human error in weight distribution. This regulatory pressure is a primary catalyst for the adoption of automated systems that provide audit trails and verification checks.
IATA plays a crucial role in standardizing the workforce through training and design manuals for aircraft weight and balance. They prepare personnel for Load Controller certification under global aviation standards, ensuring that the human element operating these systems is equally qualified. Meanwhile, EASA and equivalent military certifications apply to related control loading and weight and balance systems in both simulation and operational contexts. The evolving regulatory framework drives demand for technologies that can adapt to new rules without massive hardware overhauls. Digital solutions that receive updates remotely offer a distinct advantage in maintaining compliance across global fleets operating in different jurisdictions.
Furthermore, the push for sustainability is intertwining with load control. Centralized Load Control systems are increasingly recognized for their ability to enable fuel consumption reduction through optimized weight distribution and Easy Final Weight calculations. This alignment of safety, compliance, and environmental goals creates a strong value proposition for investing in advanced load control technologies.
Worldwide Aircraft Load Control Solution Market
Strategic Value for 2026 Decision Making
For executives and strategists operating in 2026, understanding the nuances of this market is critical. The growth trajectory indicates a maturing market where differentiation lies in integration depth and operational automation. Our report goes beyond high-level numbers to explore the practical implications of these trends. We analyze how specific solution types are penetrating different regions without exposing the precise percentage splits that require a full subscription to validate against your specific operational footprint. This approach ensures that when you access the full data, the insights are actionable for your specific context, whether you are evaluating a vendor partnership, considering a technology upgrade, or assessing market entry opportunities.
The report also addresses the shifting dynamics in ground handling. As airports seek to optimize turnaround times, the efficiency of load control processes becomes a bottleneck or a enabler. Companies that can offer seamless integration with existing airport IT infrastructure while providing robust weight and balance capabilities are likely to capture greater market share. The recent developments in centralized load control services, such as those highlighted by major ground handlers expanding their center capabilities in strategic locations, illustrate the trend toward outsourcing complex calculations to specialized centers that can achieve economies of scale.
Load Cells Market
Additionally, the distinction between cloud-based and on-premise solutions is not just about technology preference but about risk management and connectivity. In regions with intermittent connectivity, hybrid models or robust offline capabilities, as offered by certain innovators, become critical. Our analysis evaluates these capabilities against the backdrop of global travel patterns and infrastructure reliability.
Conclusion: Preparing for the Future of Load Management
The Worldwide Aircraft Load Control Solution Market is poised for significant evolution over the next seven years. The projected growth to over 275 million USD by 2032 reflects a sector that is integral to the safe and efficient operation of modern aviation. For stakeholders, the opportunity lies in selecting solutions that not only meet current regulatory standards but are adaptable enough to handle future requirements. The competition among key players is driving innovation in automation, integration, and service delivery models.
PW Consulting's comprehensive study provides the depth required to make informed capital allocation and strategic partnership decisions. By understanding the historical performance from 2020 to 2025 and the forecasted dynamics through 2032, organizations can position themselves to leverage efficiency gains and mitigate compliance risks. We invite industry leaders to explore the full findings of this report, where detailed segmentation data, comprehensive competitor profiles, and granular regional analysis await. In a market defined by precision, your strategic decisions deserve intelligence of the same caliber. Access the complete market intelligence to ensure your operations remain balanced, compliant, and competitive in the global airspace.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 5G NR Antenna Market to Hit $80.1B by 2032, 15.68% CAGR
By pmarketresearch, 2026-09-16
Navigating the 5G NR Antenna Revolution: Strategic Insights for 2026 and Beyond
The global telecommunications infrastructure is undergoing a structural transformation, driven by the relentless demand for higher throughput, lower latency, and ubiquitous connectivity. At the heart of this evolution lies the 5G NR antenna market, a critical enabler of network capacity and spectral efficiency. As we enter 2026, industry stakeholders face a complex landscape defined by rapid technological iteration, evolving regulatory frameworks, and shifting supply chain dynamics. PW Consulting's latest comprehensive market research offers a definitive guide to navigating this terrain, providing the granular intelligence necessary for informed strategic decision-making.
This report is not merely a snapshot of current revenues; it is a forward-looking strategic asset designed to help operators, equipment manufacturers, and investors align their roadmaps with market realities. By analyzing historical trajectories from 2020 through 2025 and projecting growth patterns through 2032, we uncover the underlying forces shaping the industry's next decade. The following insights distill the key findings of our analysis, highlighting why access to detailed market intelligence is indispensable for maintaining competitiveness in a consolidating and technologically intense environment.
Macro Market Trajectory and Growth Vectors
The financial scale of the 5G NR antenna sector underscores its strategic importance. Valued at approximately 12,500 million USD in 2020, the market has demonstrated aggressive expansion, reaching an estimated 28,900 million USD by the base year of 2025. This growth reflects the accelerated deployment of 5G networks across commercial and industrial sectors globally. Looking ahead, our forecasts indicate that revenue will continue to climb significantly, surpassing 33,000 million USD in 2026 and projecting toward a substantial 80,113.5 million USD mark by 2032.
Wireless Antenna Market
This trajectory corresponds to a compound annual growth rate (CAGR) of 15.68 percent over the forecast period from 2026 to 2032. Such sustained growth suggests that antenna systems will remain a high-priority capital expenditure category for network builders. However, raw market size tells only part of the story. The velocity of growth varies across technology adoptions, frequency bands, and deployment types, creating pockets of opportunity and risk that require precise navigation. Understanding the interplay between these segments is crucial for optimizing supply chain investments and R&D focus areas.
Technology and Frequency Band Dynamics
The architectural choices defining 5G NR deployments are heavily influenced by the balance between coverage requirements and capacity demands. Our analysis delves deep into the split between Sub-6 GHz and mmWave solutions, as well as the divergence between Massive MIMO and traditional SISO or Basic MIMO configurations. These technological distinctions drive different value propositions for urban dense environments versus broader rural or suburban coverage scenarios.
Massive MIMO technology, in particular, has become a cornerstone for high-capacity macro sites, allowing operators to multiplex multiple data streams and significantly improve spectral efficiency. Concurrently, the industry is witnessing a nuanced evolution in frequency band utilization. While Sub-6 GHz remains the workhorse for widespread coverage, mmWave solutions are carving out critical niches for high-throughput applications in specific locales. The report provides a detailed examination of how these technology and frequency segments interact with deployment types, distinguishing between the requirements for Macro Cells and the growing necessity of Small Cells to fill coverage gaps and enhance indoor performance.
Strategic planners must recognize that the choice of antenna technology is not isolated from infrastructure costs. For instance, the economics of fiber optic deployment for 5G backhaul, which can range significantly per kilometer, directly influence the feasibility and density of small cell deployments. Our research integrates these infrastructure cost factors to provide a holistic view of total network economics, ensuring that antenna selection aligns with broader capital efficiency goals.
Competitive Landscape and Key Player Strategies
The market structure is characterized by a mix of established telecommunications giants and specialized antenna manufacturers, creating a dynamic competitive environment. The top three companies collectively hold a significant portion of the market revenue, while the top five extend their influence further, indicating a moderately concentrated landscape where scale and technological expertise provide distinct advantages.
Ericsson and Nokia continue to lead in providing comprehensive radio access solutions, including massive MIMO and hybrid active-passive 5G NR base station antennas. Ericsson's integration of Kathrein technology and Nokia's AirScale mMIMO adaptive antennas exemplify the industry's push toward scalable radio access with passive-active integration. Huawei remains a formidable supplier of ultra-wideband Active Antenna Units (AAU) and multi-band 5G NR antennas, emphasizing energy efficiency and high-performance base station solutions for dense urban areas. Samsung contributes high-throughput massive MIMO radios and antenna systems, with strategic collaborations extending into non-terrestrial network testing.
Complementing these major players are specialized firms that address specific deployment needs. CommScope and Amphenol Antenna Solutions focus on manufacturing passive and hybrid panel and base station antennas, crucial for integrating with active radios in macro cell sites. Comba Telecom and Tongyu Communication provide robust passive and active elements for macro and distributed systems, while Tongyu's multi-band capabilities highlight the trend toward versatile antenna designs. In the realm of in-building and complex venue coverage, Corning's Everon distributed antenna systems (DAS) and JMA Wireless' TEKO and XRAN solutions offer optical and RF integration for 5G NR indoor and outdoor deployments. SOLiD specializes in ALLIANCE 5G DAS for high-density environments such as subways and arenas, and PROSE Technologies focuses on passive cellular antenna solutions optimized for performance and sustainability.
Recent developments underscore the pace of innovation. In early 2026, NEC prepared to launch a new 5G sub-6 GHz massive MIMO radio unit targeting higher throughput and lower power consumption, signaling continued pressure on energy efficiency and performance. Additionally, collaborations such as the PTCRB certification achievement by Anritsu for 5G NR NTN RF conformance test cases with Samsung highlight the expanding scope of antenna and radio technologies into satellite integration domains. These moves illustrate that competitive advantage increasingly depends on holistic ecosystem support and regulatory compliance capabilities.
Worldwide 5G NR Antenna Market
Regulatory and Infrastructure Influences Shaping Deployment
Market growth does not occur in a vacuum; it is heavily modulated by regulatory actions and infrastructure constraints. In 2025, 3GPP Release 19 introduced new over-the-air spatial emission requirements for 5G NR base station antennas, specifically to protect fixed satellite systems in the upper 6 GHz band. These specifications, detailed in 3GPP TS 38.104 and TR 38.908, mandate new test procedures and influence antenna design to ensure compliance while maintaining performance.
Simultaneously, spectrum availability remains a critical driver. US legislation (P.L. 119-21) directs the FCC to auction at least 100 MHz in the upper C-band (3.98-4.2 GHz) by July 2027, contributing to a broader 800 MHz spectrum pipeline through 2034. Furthermore, the FCC has restored auction authority through 2034 and is advancing the identification of 500 MHz in the 1.3-10.5 GHz range for commercial licensed use. These spectrum expansions will inevitably stimulate demand for antennas capable of operating across wider bandwidths and new frequency allocations.
On the infrastructure side, cost pressures persist. Fiber optic cable prices surged in early 2026 due to sustained demand from 5G backhaul and fronthaul requirements, as well as data center interconnects needing bend-insensitive and high-density cables. With average fiber deployment costs per kilometer forming a key component of overall network expenses, antenna solutions that reduce the need for extensive fiber runs or integrate efficiently with existing infrastructure gain strategic value. Our report evaluates how these regulatory and cost dynamics intersect with regional deployment strategies, helping stakeholders anticipate compliance costs and infrastructure bottlenecks.
Why This Report is Essential for 2026 Decision-Making
As the market matures, the margin for error in strategic planning narrows. Operators must decide where to deploy Massive MIMO versus SISO solutions, how to balance Sub-6 GHz and mmWave investments, and which deployment types—Macro versus Small Cells—offer the best return on investment in specific contexts. Equipment manufacturers need to anticipate shifts in demand across regions and technology segments to optimize production capacity and supply chain resilience. Investors require clarity on market concentration, growth sustainability, and the impact of regulatory changes on revenue streams.
This PW Consulting report delivers the actionable intelligence needed to address these challenges. It provides a detailed segmentation analysis across regions and application categories, offering granular data that generic industry summaries often obscure. By revealing the specific revenue contributions and growth rates within each segment, the report enables organizations to benchmark their performance, identify underserved markets, and refine their go-to-market strategies. The inclusion of company profiles and recent developments further equips readers with a competitive intelligence toolkit, highlighting who is leading in which technology domain and where the next product launches or standard updates might shift the balance of power.
Moreover, the integration of industry context noise—such as raw material price fluctuations, regulatory milestones, and infrastructure cost variables—ensures that decision-makers can stress-test their strategies against real-world disruptions. The ability to correlate antenna market data with broader telecom ecosystem trends is a distinct advantage in a sector where interdependencies are high.
Conclusion: Aligning Strategy with Market Reality
The 5G NR antenna market is poised for sustained expansion, but the path forward is nuanced. Success in 2026 and beyond will belong to those who can navigate the complexities of technology selection, regulatory compliance, and competitive positioning with precision. PW Consulting's Worldwide 5G NR Antenna Market research provides the comprehensive framework necessary to make these decisions with confidence. By transforming raw data into strategic insights, this report empowers stakeholders to capitalize on growth opportunities while mitigating risks associated with market concentration, infrastructure costs, and evolving standards.
To access the full breadth of our analysis, including detailed segmentation data, regional breakdowns, and exhaustive competitive profiles, we invite you to explore the complete report. The depth of information contained within is designed to serve as a foundational resource for your strategic planning, ensuring that your organization remains at the forefront of the 5G NR antenna revolution.
For detailed analysis of this topic, please visit the official page: Worldwide 5G NR Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Breathable Waterproof Fabrics Market to Hit USD 12,874 Million by 2032 at 7.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Evolving Breathable Waterproof Fabrics Market: A 2026 Decision-Making Framework
The global landscape for breathable waterproof fabrics is undergoing a structural transformation driven by simultaneous pressures from regulatory compliance, raw material volatility, and shifting consumer expectations around sustainability. For enterprise leaders navigating product roadmaps, supply chain strategy, and capital allocation in 2026, understanding the trajectory of this sector requires more than headline numbers. It demands a granular, data-grounded view of how material science, geographic demand centers, and application-specific performance requirements are converging to reshape competitive advantage.
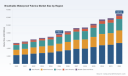
The Worldwide Breathable Waterproof Fabrics Market study provides exactly that vantage point. Built on historical performance tracking from 2020 through 2025 and extending forecast visibility through 2032, the analysis translates macro growth signals into actionable intelligence for product planners, procurement directors, and corporate development teams. The market expanded from approximately USD 5,420.5 million in 2020 to an estimated USD 7,760.11 million in 2025, and the projected trajectory points toward sustained expansion at a compound annual growth rate of 7.5 percent. By 2032, the global revenue base is expected to approach the USD 12,874.4 million threshold, reflecting a market that is maturing in scale while simultaneously fragmenting in technological and regulatory complexity.
Worldwide Breathable Waterproof Fabrics Market
This publication is designed not as a static reference document but as a decision-support instrument. Below, we outline the analytical architecture, the competitive intelligence embedded within, and the operational insights that make this research directly relevant to 2026 strategic planning.
Macroeconomic Trajectory and the Case for Forward-Looking Intelligence
Growth in breathable waterproof fabrics is no longer a simple function of outdoor apparel demand cycles. The sector is being re-shaped by durable structural forces: tightening chemical restrictions on fluorinated compounds, the commercialization of PFAS-minimized and PFAS-free membrane technologies, material cost fluctuations tied to regional industrial demand, and the expansion of performance textiles into adjacent verticals. Companies that treat these shifts as isolated events risk misaligning product specifications, supplier partnerships, and margin models.
The historical dataset within the report captures the market’s resilience through recent years of macroeconomic uncertainty. Revenue progression from 2020 to 2025 demonstrates an uninterrupted upward path, with the 2025 estimate of USD 7,760.11 million setting the baseline for the 2026 forecast year at USD 8,446.27 million. Importantly, the forecast horizon does not assume a straight-line continuation. The analysis incorporates variable growth rates across the projection window, reflecting how regulatory timelines, material substitution adoption curves, and application mix shifts will alter the pace of expansion year by year. Decision-makers using this framework can stress-test product introduction timing, capacity planning, and regional prioritization against a range of plausible near-term scenarios rather than relying on a single deterministic forecast.
Regulatory Dynamics and Material Substitution Pressure Points
Regulatory developments are now a primary driver of product development cadence and supplier selection logic. Effective from January 2025, California and New York prohibited the sale of new apparel containing intentionally added PFAS, and bluesign certification similarly restricted intentionally added PFAS from the same date, subject to limited exceptions. In Europe, France enacted Law No. 2025-188, which bans the manufacture, import, export, and sale of PFAS-containing clothing textiles and footwear beginning January 2026, with certain exemptions and a broader textile prohibition scheduled for 2030. These measures are not confined to compliance checklists; they are accelerating the commercial relevance of alternative membrane chemistries and compelling brands to re-evaluate laminate specifications across existing and future collections.
For procurement and R&D teams, the implication is clear: material decisions made today will carry regulatory exposure well into the back half of the decade. The report maps these regulatory timelines against material categories and application requirements, enabling readers to anticipate where substitution pressure will be most acute and where transitional formulations may remain viable. This is particularly critical for enterprises operating across multiple jurisdictions, where a specification acceptable in one market may become a liability in another.
Material Cost Volatility and Supply Chain Implications
Raw material pricing is another dimension where strategic foresight pays direct dividends. Polyurethane prices in Europe reached USD 3.43 per kilogram in December 2025, reflecting a modest 2.8 percent decline from September 2025 amid softer demand in construction and automotive end markets. Meanwhile, fluoropolymer prices in North America decreased 1.45 percent quarter-over-quarter in Q4 2025 due to mild oversupply. However, the broader cost picture is uneven: China’s 2025 tightening of fluorspar export licensing raised costs for Western converters by an estimated 12 to 18 percent, reshaping the economics of PTFE-based supply chains outside Asia.
Compounding these dynamics, the U.S. EPA TSCA 2024 Rule will prohibit the distribution in U.S. commerce of articles containing phenol, isopropylated phosphate (3:1) [PIP (3:1)] beginning October 31, 2026, affecting certain textile manufacturing equipment and materials. These intersecting cost and compliance variables create a complex procurement environment. The market study integrates material cost movements and regulatory milestones into a cohesive operational narrative, helping readers assess supplier diversification strategies, regional sourcing trade-offs, and inventory timing without relying on fragmented intelligence.
Segmentation Architecture: Where Value Creation Is Shifting
A defining feature of this research is its segmentation architecture, which connects material innovation, application demand, and regional consumption patterns to the broader market trajectory. Rather than treating these dimensions in isolation, the report structures them to reveal how technology adoption accelerates or slows in different use cases, and how regional supply ecosystems influence competitive positioning.
Worldwide Breathable Membranes Market
On the material side, ePTFE-based membranes continue to anchor a substantial share of performance-oriented applications, while polyurethane and polyester-based systems are gaining relevance as manufacturers pursue recyclability, cost efficiency, and PFAS-reduced or PFAS-free formulations. This is not a simplistic substitution story. Each material class carries distinct trade-offs in breathability, durability, processability, and end-of-life characteristics, and the report examines how these trade-offs play out across major application verticals. Sportswear and activewear remain a dominant demand center, but protective clothing, medical and hygiene applications, and automotive and industrial uses each present different performance thresholds and procurement dynamics that influence both product design and supplier selection.
Regionally, the market reflects a multi-polar demand structure rather than a single dominant geography. Asia Pacific represents the largest consumption base, supported by broad manufacturing capacity and growing domestic demand for performance textiles. North America and Europe continue to function as high-value demand centers with particular sensitivity to regulatory standards and premium performance specifications. Latin America and the Middle East and Africa constitute smaller but strategically relevant markets where cost structure, supplier proximity, and application mix can differ meaningfully from the major regions. The study provides the analytical spine to evaluate these regional profiles without reducing them to simplistic rankings, giving readers the context needed to align product launches, distribution strategies, and partnership models with local market realities.
Because the report’s full segmentation detail—including region-level revenue allocations, material-category breakdowns, and application-specific market sizes—contains precisely the kind of granular intelligence that supports forecasting, pricing strategy, and competitive benchmarking, it is reserved for the complete publication. This deliberate structure ensures that enterprise teams can evaluate the strategic shape of the market here while accessing the quantitative depth required for operational planning through the source report.
Competitive Landscape: Incumbents, Specialists, and Disruption Vectors
The competitive field in breathable waterproof fabrics is characterized by a mix of established membrane specialists, material innovators, and integrated sportswear producers that have moved upstream into proprietary fabric development. Concentration metrics indicate a moderately consolidated environment, with the top three players accounting for an estimated 38.5 percent of market revenue and the top five approaching 52.2 percent. That level of concentration suggests both the presence of scale advantages and the continued room for specialized entrants that can differentiate on technology, sustainability credentials, or application-specific performance.
W. L. Gore & Associates remains a central reference point, with its GORE-TEX ePTFE-based waterproof breathable membranes and laminates widely deployed across outdoor apparel, footwear, and protective gear. Gore’s recent introduction of next-generation GORE-TEX Pro with an ePE membrane illustrates the broader industry pivot toward minimizing intentionally added PFAS while preserving durability for demanding use cases. Toray Industries supplies polyurethane and TPU-based systems through platforms such as Dermizax, supporting both performance apparel and industrial applications. SympaTex Technologies has built a distinct position around recyclable polyester-based membranes, while schoeller Textil AG continues to develop high-performance waterproof breathable textiles for outdoor and workwear segments. Polartec contributes NeoShell and related laminates integrated into performance fabrics, and eVent Fabrics has focused on direct-venting membrane architectures, including recent collaboration on moisture-managing systems.
The competitive frontier is also expanding through emerging technology providers and vertically integrated sportswear brands. FORMOSA TAFFETA operates at large scale in coated and laminated waterproof breathable fabrics for apparel and technical textiles, and HeiQ Materials supplies functional treatments and membrane-enhancing technologies. In Switzerland, dimpora has advanced PFAS-free CoreLayer Technology membranes with a circularity focus, while ANTA Sports Products has pushed commercialization through the launch of AEROVENT ZERO, a mass-produced PFAS-free bio-based waterproof breathable membrane integrated into next-generation storm jackets, with projected sales exceeding 500,000 units by 2026.
Recent corporate activity underscores how quickly the competitive baseline is moving. In August 2025, ANTA and Donghua University announced the global launch of AEROVENT ZERO as China’s first independently developed high-performance PFAS-free bio-based waterproof-breathable membrane. In September 2025, Gore updated its portfolio with the ePE-based GORE-TEX Pro launch. By March 2026, Surforce Technology Group reported a major advance in functional nanofiber nonwoven materials, addressing long-standing limitations of traditional PTFE and TPU membranes in breathability and elasticity, supported by a ten-million-meter-scale nanofiber factory. That same month, eVent Fabrics partnered with ALLIED Feather + Down to debut a moisture-managing system combining eVent’s 2-layer stormburstLT laminate with ExpeDRY down at Performance Days Munich.
These developments are not isolated press items; they are signals of where value is migrating. The study profiles these companies and contextualizes their moves within technology roadmaps, regulatory exposure, and application expansion. Readers gain a structured view of who is competing on scale, who is competing on material architecture, and who is attempting to disrupt through bio-based or PFAS-free approaches with different performance and cost profiles.
Strategic Applications for 2026 Decision-Making
For executives planning 2026 initiatives, the research is designed to support several interconnected decision domains. Product strategy teams can use the forecast and segmentation framework to prioritize development resources toward applications where performance demand, regulatory tailwinds, or pricing power are most favorable. Procurement and supply chain leaders can align supplier negotiations with material cost trajectories, regional cost differentials, and anticipated compliance constraints. Corporate development and M&A teams can identify technology partnerships and acquisition targets based on membrane chemistry, sustainability positioning, and geographic footprint. Brand and marketing leaders can calibrate claims and collection planning around the evolving regulatory environment, particularly as PFAS restrictions broaden and certification regimes tighten.
The report’s value lies in combining a macro growth narrative with the operational detail that makes growth actionable. It does not simply describe that the market is expanding; it clarifies where expansion is being generated, what material and regulatory shifts are shaping that expansion, and how leading companies are positioning themselves to capture it.
What the Full Study Delivers
Beyond the strategic framework summarized here, the complete Worldwide Breathable Waterproof Fabrics Market report provides a comprehensive analytical toolkit. It includes historical and forecast market sizing with year-by-year projections, a detailed segmentation structure that connects materials, applications, and regions to revenue flows, and a competitive landscape section that profiles key companies, their core offerings, and recent strategic developments. The study also integrates regulatory timelines, raw material pricing movements, and technology milestones into a unified market context, enabling readers to assess both opportunities and risk exposures in a single reference framework.
Operational users will find value in the way the report connects demand drivers to supply-side realities. Rather than presenting segmentation as an abstract taxonomy, the analysis shows how material categories interact with application requirements, how regional demand profiles are shaped by local manufacturing capacity and regulatory regimes, and how competitive dynamics differ across market segments. This makes the document suitable for cross-functional use, from product planning and procurement to market entry strategy and investor communications.
Conclusion: Positioning for a Market in Transition
The breathable waterproof fabrics market in 2026 is defined by the intersection of durable growth, regulatory redirection, and material innovation. The macro trajectory points toward continued expansion, but the more strategically important story is how that growth is being redistributed across technologies, applications, and geographies as companies respond to PFAS restrictions, cost volatility, and consumer expectations around sustainability and performance.
Organizations that base their 2026 decisions on a structured, forward-looking view of these dynamics will be better positioned to manage supplier risk, time product introductions, and allocate innovation investment effectively. The Worldwide Breathable Waterproof Fabrics Market research is built to support that effort, offering both the strategic narrative and the segmentation intelligence required to move from awareness to action.
To access the complete dataset, company profiles, segmentation detail, forecast tables, and the full set of strategic recommendations, please visit the source page for the Worldwide Breathable Waterproof Fabrics Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Breathable Waterproof Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hydrochar Market Hits $285.5M in 2025, Projected 8.5% CAGR to 2032
By pmarketresearch, 2026-09-16
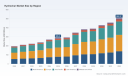
Strategic Horizons in the Global Hydrochar Market: Navigating the 2032 Outlook
The global transition toward circular carbon economies is no longer a theoretical ambition. It is a measurable industrial shift, and nowhere is this more evident than in the rapidly maturing hydrochar sector. Hydrothermal carbonization has evolved from a niche laboratory process into a commercially viable pathway for converting wet organic residues into stable, energy-dense carbon materials. For executives, investors, and policy strategists operating in 2026, the question is no longer whether hydrochar will scale, but how market participants will position themselves within a rapidly fragmenting and capital-intensive landscape. This analysis draws from PW Consulting's latest worldwide hydrochar market research, offering a strategic preview of the macroeconomic trajectory, competitive architecture, and operational levers that will define the next seven years.
Market Trajectory: From Acceleration to Structural Scaling
The hydrochar market is entering a phase of compounding structural growth rather than cyclical fluctuation. Historical revenue data from 2020 through 2025 demonstrates a consistent upward arc, reflecting the gradual commercialization of hydrothermal carbonization (HTC) and related conversion technologies across municipal waste management, industrial biomass processing, and agricultural valorization networks. From an analytical perspective, the transition into the 2026–2032 forecast window marks a critical inflection point, as scaling effects, regulatory alignment, and feedstock logistics begin to converge.
The market size trajectory underscores this momentum. Starting at approximately 195.4 million USD in 2020, revenue climbed steadily to 285.5 million USD by the base year of 2025. This historical run-rate establishes a firm foundation for the forecast period, with projected revenue expanding to 292.49 million USD in 2026 and accelerating toward 345.9 million USD by 2027. The trajectory continues upward through the decade, culminating in a projected market valuation of 505.37 million USD by 2032. When annualized, this pathway translates to a compound annual growth rate of 8.5 percent, a figure that places hydrochar among the more resilient subsegments within the broader bioenergy and carbon management ecosystem. For corporate strategists, an 8.5 percent CAGR is not merely a growth indicator; it is a signal that supply chain investments, technology partnerships, and capacity planning must be calibrated against a compounding demand environment rather than a static market structure.
Regulatory Catalysts and Feedstock Dynamics
Market expansion in the hydrochar space is being reinforced by a convergence of regulatory mandates and structural feedstock advantages. In Europe, the revised Waste Framework Directive (2008/98/EC) has established binding timelines for the separate collection of biowaste, fundamentally altering municipal waste management economics. This policy shift is expected to accelerate the deployment of HTC-based pathways, as municipalities and industrial processors seek compliant, high-value utilization routes for wet organic streams that would otherwise incur high transportation and disposal costs.
The raw material landscape further amplifies this trajectory. IEA Bioenergy Task 40 has identified roughly 200 million metric tons per year of available wet biomass residues across Europe alone, a volume that provides substantial feedstock headroom for hydrothermal conversion. This availability is critical because hydrochar production inherently favors wet biomass, circumventing the energy-intensive drying requirements that constrain conventional pyrolysis operations. From a technical standpoint, hydrothermal processing achieves a carbon yield in the range of 70 to 80 percent from initial biomass, while simultaneously densifying the energy content to approximately 25 MJ/kg, positioning the output as both a soil amendment and a drop-in solid fuel.
Carbon pricing mechanisms are adding commercial momentum. Under current European Union Emissions Trading System guidelines, the co-firing of hydrochar in industrial and power generation settings can qualify for carbon credit recognition, given that the process can reduce CO2 emissions by up to 90 percent relative to conventional coal combustion. This reimbursement dynamic transforms hydrochar from a waste-management solution into a monetizable decarbonization asset, enabling power generators and heavy industry operators to integrate hydrochar into existing combustion infrastructure with measurable compliance benefits. In parallel, macroeconomic planning in Asia is creating import and scaling pathways. China's 14th Five-Year Plan explicitly targets a 20 percent share for biomass energy, establishing a policy environment that supports both domestic development and cross-border procurement of hydrochar products and technology partnerships.
Segmentation and Application Architecture
The revenue architecture of the hydrochar market reflects a diversified application base, with material valorization and energy recovery operating as parallel growth engines. Rather than relying on a single end-use vertical, the market distributes demand across soil and fertilizer applications, solid fuel and energy generation, and activated carbon or adsorbent production. This tripartite composition provides structural resilience, as fluctuations in one application segment can be partially offset by demand in another. Soil amendment and fertilizer utilization remains a foundational demand channel, particularly as agricultural sectors seek organic carbon-based soil conditioners that improve water retention, nutrient availability, and long-term carbon sequestration.
Simultaneously, the solid fuel and energy generation pathway has emerged as the largest demand driver in the current market structure. Hydrochar's compatibility with existing combustion systems, combined with its elevated energy density and low moisture content after processing, enables industrial boilers, co-firing facilities, and dedicated bioenergy plants to substitute a portion of their fossil fuel inputs with a renewable carbon carrier. The activated carbon and adsorbents segment represents a higher-value, performance-driven market, where hydrochar serves as a precursor for filtration media, contaminant capture, and industrial purification applications. This segment's growth is tightly coupled with tightening environmental standards across water treatment, air quality management, and industrial process control.
Feedstock type segmentation further illustrates the market's adaptability. Sewage sludge, agricultural waste, and food waste each contribute meaningful volumes, with the relative attractiveness of each stream varying by regional waste management infrastructure, local regulatory frameworks, and downstream end-use requirements. Sewage sludge conversion benefits from established municipal collection systems and high moisture content that aligns well with hydrothermal processing. Agricultural residues provide a geographically distributed feedstock base with strong seasonal availability, while food waste streams offer concentrated organic content suitable for localized conversion facilities. The optimal feedstock mix is rarely static; it is shaped by logistics costs, subsidy structures, and the proximity of conversion capacity to both waste generation points and end-use markets.
Competitive Landscape: Technology Positioning and Corporate Strategy
The competitive structure of the hydrochar market remains moderately fragmented, with the top three participants collectively capturing approximately 28.5 percent of market revenue and the top five firms extending that share to roughly 35.2 percent. This concentration pattern indicates that while scale advantages are materializing, the market has not yet consolidated around a small number of dominant incumbents. The current competitive environment is instead defined by differentiated technology pathways, geographic specialization, and application-specific product positioning.
Ingelia, headquartered in Barcelona, Spain, has established itself as a reference point for commercial HTC deployment, particularly in the conversion of sewage sludge and biowaste into fertilizer and fuel-grade hydrochar. The company's operational footprint advanced significantly in November 2022, when it initiated operations at a 7,000 ton-per-year hydrochar plant in Italy, demonstrating the feasibility of medium-scale, continuous conversion infrastructure processing municipal sewage streams. This milestone highlights the commercial viability of integrating HTC into existing wastewater and waste-to-resource networks.
TerraNova Energy GmbH, based in Münster, Germany, has pursued an industrial-scale strategy through its HTCycle technology, targeting wet biomass residues for both energy and soil applications. The company reinforced its market trajectory in June 2023 by securing a contract for a HTCycle plant in Germany designed to produce approximately 20,000 tons per year of hydrochar from biowaste. This contract reflects a strategic emphasis on large-capacity facilities that leverage European biowaste collection mandates and industrial decarbonization requirements.
BlackCarbon GmbH, operating from St. Pölten, Austria, has carved out a premium positioning by manufacturing hydrochar from wood waste and agricultural residues, specifically designed as a drop-in coal replacement for industrial boilers. In March 2023, the company expanded its facility to a 10,000 ton-per-year capacity, signaling commitment to scaling a product line that prioritizes combustion compatibility and energy substitution in industrial heat applications.
Arbaflame A/S, headquartered in Aarhus, Denmark, has pursued a standardized pellet product strategy with its Arbacore hydrochar pellets, targeting co-firing applications in power plants as a sustainable coal alternative. This approach aligns with the broader energy transition demand for standardized, transportable biomass-derived fuels that can be integrated into existing power generation logistics without extensive boiler modifications.
Haffner Energy, based in Vitry-le-François, France, focuses on its ERC technology for generating SynChar hydrochar from wet organic waste, targeting energy production and carbon storage applications. The company achieved an important validation milestone in September 2022 with the certification of its ERC pilot plant for 1 ton-per-day SynChar production from agricultural waste, a step that supports its pathway toward commercial scaling and process refinement.
Worldwide Hydrochar Market
Hydrocracker Market
Antaco, operating from Santiago, Chile, illustrates the geographic diversification of the market by producing hydrochar from forestry residues and sewage sludge for soil amendment and biofuel markets across South America. The company's business model reflects the applicability of hydrochar technologies beyond European and North American regulatory contexts, demonstrating that feedstock availability, agricultural soil needs, and bioenergy demand can jointly support commercial deployment in emerging regional markets.
Strategic Decision Points for 2026 Leadership
For corporate leaders and investment decision-makers, the hydrochar market presents a set of interlocking strategic choices. The first is feedstock positioning. Given the diversity of viable input streams and the strong dependence on local logistics, companies must assess whether to align with municipal waste management contracts, agricultural residue supply networks, or industrial organic waste partnerships. Feedstock security is not merely an operational concern; it is a determinant of capacity utilization, revenue predictability, and margin stability.
The second decision point is application-market alignment. Facilities and technologies optimized for solid fuel substitution may require different product specifications, quality controls, and commercial partnerships than those targeting soil amendment or activated carbon production. The market does not reward generic product strategies. Instead, it increasingly favors architectures in which conversion capacity, downstream offtake agreements, and quality certification are integrated around a clearly defined end-use pathway.
The third strategic dimension is geographic and regulatory exposure. European biowaste mandates, carbon credit eligibility under emissions trading frameworks, and Asia's biomass energy targets create differentiated opportunity sets across regions. Market participants need to evaluate where regulatory tailwinds will most rapidly convert into contracted demand, and where infrastructure gaps, feedstock competition, or certification requirements may slow commercialization. The presence of a market concentration level in the high twenties to mid-thirties percent range further suggests that early positioning in underserved regional demand centers or specialized application niches can yield meaningful competitive insulation before later-stage consolidation pressures intensify.
Finally, capital allocation and partnership strategy will play a decisive role. The recent expansion and contracting activity observed among leading firms demonstrates that capacity scaling is being undertaken in phases, often anchored by specific feedstock contracts or downstream offtake arrangements. Market entrants and existing players alike are likely to benefit from structured collaborations that distribute technology risk, align feedstock sourcing with conversion capacity, and secure revenue visibility through multi-year offtake or joint operating models.
Conclusion: Why Comprehensive Market Intelligence Matters in 2026
The worldwide hydrochar market is entering a decade in which growth will be defined less by macroeconomic cyclicity than by regulatory momentum, feedstock logistics, and application-specific commercialization. The macro trajectory points toward sustained expansion, with the market advancing from approximately 285.5 million USD in 2025 to a projected 505.37 million USD by 2032 at a compound annual growth rate of 8.5 percent. Yet macroeconomic direction alone is insufficient for rigorous corporate planning. Effective strategy demands segmentation clarity, regional demand mapping, feedstock cost modeling, technology benchmarking, and competitive intelligence that links corporate developments to broader market shifts.
PW Consulting's Worldwide Hydrochar Market research is designed to provide that operational depth. The study integrates baseline and forecast revenue structures, segmentation analysis across regions, feedstock types, and application channels, and a detailed competitive assessment of the companies actively shaping the commercial landscape. It examines the regulatory, raw material, carbon pricing, and macroeconomic developments that are altering demand formation, while offering practical context for capacity planning, partnership evaluation, and market-entry decisions.
Full segmentation figures, regional revenue distributions, detailed company positioning, and forecast scenarios are available within the complete study. Readers seeking to translate the market's directional momentum into actionable 2026 strategy are encouraged to access the full report for comprehensive data, granular segmentation breakdowns, and the competitive intelligence required to benchmark opportunities against current industry dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Heavy Truck Battery Swap Market Hits $1.25B in 2025, Projects 21% CAGR to 2032
By pmarketresearch, 2026-09-16
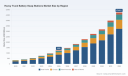
The 2026 Inflection Point: Strategic Intelligence for the Worldwide Heavy Truck Battery Swap Stations Market
The commercial transportation sector stands at a definitive crossroads. As decarbonization mandates harden and total cost of ownership models shift, battery-electric heavy trucks are transitioning from pilot programs to scaled deployment. Yet the charging bottleneck remains the single greatest barrier to fleet electrification at scale. Battery swap technology has emerged as the structural solution to this challenge, and 2026 marks the year the industry moves from proof-of-concept to commercial reality. Our newly released Worldwide Heavy Truck Battery Swap Stations Market research delivers the granular intelligence executives need to allocate capital, design infrastructure strategies, and secure competitive positioning in a market projected to surge from USD 1,250.0 million in 2025 to USD 4,746.9 million by 2032, reflecting a compound annual growth rate of 21.0 percent across the 2026–2032 forecast window.
This research is engineered not as a passive data repository but as a decision architecture tool. Every section is calibrated to answer the strategic questions that will define boardroom conversations in 2026: Where does capital flow most efficiently? Which operational models will dominate early-adopter corridors? How do regulatory interventions reshape unit economics? And which players are building defensible moats versus those riding temporary policy tailwinds? The following analysis outlines the strategic architecture of this intelligence, demonstrating how it translates market complexity into actionable executive roadmap components.
A Market Trajectory Defined by Acceleration and Structural Rebalancing
The growth curve tells a story of accelerating commercial validation. Revenue expanded from USD 350.0 million in 2020 to USD 427.88 million in 2021, then accelerated through USD 543.2 million in 2022 and USD 750.94 million in 2023 as infrastructure rollouts moved beyond demonstration phases. The trajectory crossed the one-billion threshold at USD 968.97 million in 2024, reached USD 1,250.0 million in 2025, and is projected to climb to USD 1,474.17 million in 2026 before scaling to USD 1,839.2 million in 2027, USD 2,279.85 million in 2028, USD 2,768.68 million in 2029, USD 3,189.24 million in 2030, USD 3,995.27 million in 2031, and ultimately USD 4,746.9 million in 2032. This expansion is not linear; it reflects compounding effects of standardized hardware deployment, fleet-scale procurement cycles, and localized incentive architectures aligning with route-specific utilization patterns.
For executives, the critical insight lies in recognizing that 2026–2028 represents a positioning window where early infrastructure commitments secure operational corridors, while delayed entry forces negotiation from a disadvantaged position as asset utilization rates climb and site availability contracts. The research maps these inflection dynamics across multiple commercial variables, enabling scenario modeling that accounts for deployment pacing, regulatory timeline shifts, and capital expenditure phasing.
Decoding the Commercial Architecture: Segmentation Logic and Deployment Realities
The market does not grow uniformly across geographies or operational configurations. Regional deployment patterns reveal distinct maturity curves, with Asia Pacific commanding the largest revenue share at USD 852.66 million, followed by Europe at USD 218.48 million, North America at USD 128.21 million, and Rest of World at USD 50.65 million. These distributions reflect differences in freight corridor density, policy sequencing, grid integration timelines, and the progression of truck manufacturing ecosystems. The research dissects the underlying drivers behind each regional trajectory, examining how corridor-specific freight volumes, municipal permitting structures, and cross-border trade routes influence station siting economics and utilization forecasts.
Station architecture introduces another strategic dimension. Automated swap stations, representing USD 954.28 million of the segmentation landscape, deliver throughput advantages critical for high-utilization fleet corridors, while semi-automated configurations at USD 295.72 million offer capital flexibility for phased rollouts and lower-density routes. Operation models further diversify strategic considerations: fleet-dedicated stations at USD 699.11 million align with captive logistics networks seeking predictable turnaround cycles, whereas public access stations at USD 550.89 million address multi-operator utilization and emerging commercial ecosystems. Each segment carries distinct capex profiles, utilization thresholds, and margin trajectories, all of which are mapped in detail within the full report to support deployment sequencing decisions.
The competitive structure adds another layer of strategic complexity. Market concentration metrics show a CR3 of 65.2 percent and a CR5 of 78.4 percent, indicating that early-mover positioning and standardized ecosystem control are consolidating rapidly. This concentration underscores the urgency of strategic timing: as leading operators scale standardized networks and secure preferential site access, late entrants face increasing structural friction in building comparable throughput economics.
Operational Economics, Grid Integration, and the Policy Multiplier
Infrastructure deployment cannot be evaluated in isolation from the operational and regulatory environment that shapes unit economics. Station construction requires substantial upfront investment, with costs typically ranging from RMB 15 million to RMB 25 million per site when accounting for civil works, battery procurement, and grid upgrades. Grid integration demands are equally consequential, as stations require minimum 2MVA connection capacity to support simultaneous swap operations involving multiple heavy battery packs. These technical thresholds directly influence site selection logic, permitting timelines, and the economic viability of high-throughput configurations.
Battery economics form the core variable in total cost calculations. Heavy truck swap batteries in the 500–700kWh LFP range trade in bulk at approximately RMB 800 to RMB 1,200 per kWh, making procurement scale, cycle-life management, and second-life utilization pathways critical margin determinants. The research models these cost structures alongside utilization scenarios to identify the throughput thresholds at which station economics transition from marginal to accretive, providing executives with clear deployment pacing benchmarks.
Policy architecture functions as a strategic accelerator. Chinese local governments have structured subsidy frameworks offering up to RMB 10 million per heavy truck battery swap station under new infrastructure initiatives, materially improving early-stage payback profiles. Simultaneously, standardization efforts have gained formal traction. The MIIT group standard T/CAMPEV 115-2023, released in October 2023, specifies battery voltage compatibility up to 1000V and mandates swap completion times under six minutes for heavy trucks. This standard establishes the technical baseline for interoperability and reduces the fragmentation risk that historically plagued early swap ecosystems. The report maps how these regulatory instruments interact with corporate capital deployment cycles, enabling executives to anticipate subsidy utilization windows, compliance timelines, and interoperability requirements across different jurisdictions.
Competitor Positioning: Who Is Building Scale and Who Is Building Standards
The competitive landscape is defined by a concentrated group of infrastructure and vehicle ecosystem players advancing parallel but increasingly intersecting strategies. CATL, headquartered in Ningde, China, operates the Tianfu Battery Swap Network, deploying standardized heavy-duty truck battery swap stations engineered for 5-minute swap cycles on 500kWh+ battery packs. Its November 2023 commissioning of the world's first standardized heavy-duty truck battery swap station in Yibin, Sichuan, supporting Sinotruk vehicles, signals a shift from component supply to integrated infrastructure ownership, positioning the company at the intersection of battery standardization and station-level throughput optimization.
Worldwide Heavy Truck Battery Swap Stations Market
Farizon Auto, based in Hangzhou, China, has advanced its V5 SuperSwap station network to support Geely's electric logistics vehicles through modular battery swapping architectures. The September 2023 launch of its first heavy truck swap station in Hangzhou marked an early operational footprint for a vehicle manufacturer building parallel infrastructure capability, a model that ties station economics directly to captive fleet deployment and reduces interoperability uncertainty in early corridor rollouts.
TGOOD, headquartered in Shenzhen, China, delivers integrated battery swap solutions spanning heavy-duty trucks and logistics applications, with commercial stations already operational across multiple Chinese provinces. Its multi-provincial footprint illustrates the importance of geographic diversification and operational learning curves in refining station throughput, maintenance cycles, and localized grid coordination strategies.
Aulton New Energy, based in Wuxi, China, extends its bus swap technology heritage into heavy truck applications, offering turnkey swap stations featuring automated battery handling systems. Its cross-segment technology transfer highlights a strategic pathway where standardized mechanical handling, control software, and safety protocols developed in higher-volume transit applications are adapted to the heavier payload and higher voltage requirements of commercial truck corridors.
The recent development timeline confirms that 2023 represented an acceleration point. Between September and November 2023, the ecosystem advanced on multiple fronts: a flagship station commissioning, a formal interchangeability standard from the Ministry of Industry and Information Technology, and the launch of a manufacturer-led network node. These milestones collectively illustrate how standardization, hardware deployment, and vehicle ecosystem alignment are converging to reduce the fragmentation risk that previously constrained commercial scalability.
What the 2026–2032 Forecasting Framework Delivers
Executive decision-making under capital allocation pressure requires more than directional market sizing. The research is structured to support scenario-driven planning across multiple decision dimensions. It combines historical performance tracking from 2020 through 2025 with forward-looking forecasting across the 2026–2032 window, enabling readers to test deployment pacing assumptions against revenue trajectories, utilization thresholds, and capitalization timing.
The report examines station type economics in operational context, contrasting the throughput advantages and capex intensity of fully automated configurations against the flexibility and phased deployment logic of semi-automated sites. It evaluates operation model divergence between fleet-dedicated deployments, which prioritize turnaround predictability and captive utilization, and public access models, which pursue multi-operator aggregation and broader corridor coverage. Regional deployment logic is analyzed through the lens of corridor density, policy sequencing, and infrastructure readiness, rather than through static market share tables, ensuring that executives understand the underlying conditions that shape where and when station networks achieve economic viability.
Competitive intelligence goes beyond corporate profiling to map strategic posture, technology positioning, and deployment sequencing. The analysis identifies which players are prioritizing standardized interchangeability, which are aligning station rollout with captive vehicle procurement, and how recent standardization milestones alter the barrier profile for new entrants. This competitive mapping is integrated with market concentration dynamics to clarify the window during which partnership, site acquisition, and standardization adoption decisions carry the highest strategic leverage.
From Intelligence to Execution: Why 2026 Demands Precision Planning
The growth trajectory, regulatory architecture, and competitive consolidation visible in the current market phase create a narrow planning horizon. Capital deployment decisions made in 2026 will determine whether organizations secure high-utilization corridors or enter as followers competing for constrained site availability and secondary freight routes. The research equips executives to navigate this window by translating market scale projections into deployment sequencing logic, regulatory timing into capital phasing strategies, and competitor movement into partnership and positioning options.
For fleet operators, the intelligence clarifies the throughput and utilization thresholds at which swap station access transitions from operational experiment to structural advantage. For infrastructure developers and equipment suppliers, it identifies the site economics, grid integration requirements, and standardization trajectories that shape bankability and scale potential. For investors and strategic advisors, the concentration dynamics and regional deployment sequencing provide a framework for evaluating where value capture is most likely to accrue as the market matures from early infrastructure buildout toward broader corridor integration.
The full report expands every dimension outlined here into a comprehensive strategic architecture. It integrates detailed segmentation analysis, operational cost modeling, regulatory impact mapping, competitive positioning frameworks, and forward-looking scenario structures designed specifically for 2026 capital allocation and infrastructure planning cycles. The macro trajectory, the standardization milestones, the site economics, and the competitor deployment patterns documented within provide the evidence base required to move from market awareness to execution readiness.
Worldwide Substation Battery Market
Access the complete Worldwide Heavy Truck Battery Swap Stations Market research to secure the full segmentation breakdowns, competitor strategy maps, regional deployment logic, and scenario-planning frameworks that transform market intelligence into boardroom-ready strategy. In a market advancing at a 21.0 percent compound growth rate toward a 2032 revenue milestone above USD 4.7 billion, the organizations that move with precision in 2026 will define the infrastructure corridors and standardization standards that shape the next decade of heavy truck electrification.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Die Cutting Market Hits $6.55 Billion in 2025, Forecasted to Reach $9.12 Billion by 2032
By pmarketresearch, 2026-09-16
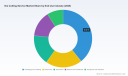
Strategic Intelligence for a Transforming Market: Introducing the Worldwide Die Cutting Service Market Research
The global die cutting service industry stands at a critical inflection point. With the market projected to reach approximately $9.12 billion by 2032 and a compound annual growth rate of 4.85 percent across the forecast horizon, the sector is no longer defined solely by mechanical precision or steady manufacturing demand. It is being reshaped by material cost volatility, sustainability mandates, accelerated technology adoption, and an increasingly fragmented competitive landscape. For executives navigating procurement strategy, capacity planning, or market entry decisions in 2026, superficial summaries are no longer sufficient. This article previews the strategic architecture of our latest Worldwide Die Cutting Service Market research and outlines why this intelligence is essential for decisive, future-ready corporate action.
A Data-Backed View of Market Momentum: 2020 Through 2032
Our analysis tracks a clear upward trajectory across the historical and forecast periods. From 2020 through 2025, the market expanded from roughly $5.12 billion to $6.55 billion, reflecting resilience despite macroeconomic pressures, supply chain realignment, and raw material price fluctuations. The forecast period from 2026 to 2032 extends that momentum, with revenue climbing through 2028 before a notable acceleration drives the market toward its 2032 endpoint. The overall trajectory underscores a structurally growing demand environment rather than a cyclical spike, but growth is not uniform. It is being pulled forward by specific process innovations, regional production shifts, and end-use industries that demand tighter tolerances, faster turnaround, and increasingly sustainable material formats.
Worldwide Die Cutting Service Market
For corporate strategists, this pattern matters because it reveals where investment and differentiation are likely to compound. The forecast period does not simply show higher aggregate revenue; it highlights a market in which operational capability, technological readiness, and regulatory compliance will increasingly separate winners from commoditized service providers. Decision-makers who understand the underlying drivers early can align capacity, vendor selection, and product-development roadmaps accordingly, rather than reacting after cost structures or customer expectations have already shifted.
Why This Research Is Designed for 2026 Decision-Makers
The Worldwide Die Cutting Service Market research is built around actionable clarity, not abstract market description. It is structured to support board-level planning, operations leadership, procurement strategy, and competitive positioning. The report integrates market sizing, segmentation, competitive profiling, and recent industry developments into a single decision-oriented framework. Readers will find a detailed mapping of process types, end-use applications, and regional demand patterns, alongside practical insights on how technology adoption and regulatory change are altering cost dynamics and service expectations.
Beyond descriptive market structure, the study examines the strategic implications of recent capital investments, equipment launches, and corporate transactions that are reshaping service capabilities. It also contextualizes raw material pricing trends and policy developments that directly affect conversion economics and compliance planning. The goal is to give executives a defensible basis for evaluating supplier partnerships, assessing technology upgrade priorities, and anticipating where service requirements will tighten over the next several years. Rather than delivering a static snapshot, the research is designed to support scenario planning in an environment where pricing, capacity, and sustainability expectations are all moving at once.
Segmentation and Demand Drivers: Where Value Is Concentrating
The market is shaped by three structural dimensions: process type, end-use industry, and regional demand. Each dimension carries distinct implications for service providers and buyers.
Process Landscape and Capability Shifts
Die cutting services are delivered through multiple conversion methods, each with different throughput characteristics, precision profiles, and capital requirements. Rotary die cutting remains a dominant pathway for high-volume production, particularly where speed, repeatability, and integrated printing or converting capabilities are essential. Flatbed die cutting continues to serve applications that demand flexibility, precision geometry, and lower setup friction for shorter runs or more complex layouts. Laser die cutting adds a further dimension by enabling intricate cuts and reducing tooling dependency in specialized use cases. Alongside these established approaches, additional process variants support niche requirements and hybrid converting workflows.
From a strategic standpoint, the relevant question is not which process is largest in isolation, but where demand is migrating as customers balance volume efficiency against customization, waste reduction, and compliance-driven material changes. The report evaluates how service providers are positioning themselves across these process categories and where equipment investment is likely to widen competitive gaps.
End-Use Industries as Demand Anchors
Demand for die cutting services is distributed across a diversified set of end-use industries, each with different performance requirements and procurement cycles. Packaging and labeling continues to be a central demand driver, reflecting the ongoing need for precise blanks, inserts, protective structures, and labeled components across consumer goods, e-commerce, and industrial supply chains. Electronics represents another significant demand pool, where tight tolerances, clean processing, and specialized material handling are increasingly important. Automotive applications add further volume and complexity, particularly as component specification and lightweighting requirements tighten. Medical and healthcare demand introduces strict quality, traceability, and material-compatibility expectations. Aerospace and industrial applications complete the picture with specialized performance thresholds and lower-volume but higher-value part requirements.
Importantly, these end-use segments do not grow in lockstep. Their relative influence on market expansion depends on production localization, regulatory pressure on materials, and the pace of product innovation. The research dissects how each vertical shapes service expectations and where suppliers can capture differentiation through process control, material expertise, or integrated converting capabilities.
Regional Demand and the Geography of Service Delivery
Regional demand patterns reflect broader manufacturing footprints, packaging consumption habits, and local regulatory environments. North America and Europe remain major demand centers with mature service ecosystems, while Asia Pacific stands out for its scale and ongoing production-network expansion. Latin America and the Middle East and Africa contribute additional regional demand, though from smaller bases, and are influenced by import dynamics, localized manufacturing strategies, and evolving logistics patterns.
Because regional markets differ in cost structures, supplier density, and compliance obligations, a single global strategy rarely fits all operating contexts. The report maps these regional differences in a way that helps organizations assess where to consolidate sourcing, where to diversify supply, and where regional capability gaps may create strategic risk or opportunity.
Competitive Landscape and Strategic Positioning
The competitive environment in die cutting services is characterized by a wide mix of specialized converters, packaging-focused service providers, and broader industrial material suppliers. Market concentration remains relatively modest at the top tier, with the top three firms holding a combined share in the low double digits and the top five firms still occupying a limited portion of total market revenue. This fragmentation suggests that scale alone is not the only route to advantage. Service quality, material versatility, process flexibility, and customer-specific engineering capability continue to matter deeply, especially in applications where precision, turnaround speed, and compliance are decisive.
Several U.S.-based specialists illustrate the depth of capability across the market. Colvin-Friedman Company has built a long-standing reputation for precision custom die cutting across more than twelve industries, emphasizing material versatility and decades of converting experience. Mills Industries focuses on precision die cutting for custom plastic corrugated packaging, including inserts, dividers, dunnage, bins, and protective solutions. LMI Packaging concentrates on precision die-cutting for lids and labels in packaging applications, with an emphasis on quality and strict specification requirements. Janco, Inc. delivers custom die cutting services for foam, plastic, and related materials across packaging, industrial, and medical sectors using rotary, flatbed, and steel rule methods. MCL Industries Inc. operates as a leading provider of rotary and flatbed die cutting services for plastics, foams, and related materials, offering turnkey converting for high-volume packaging production. Best Cutting Die supplies custom dies and die cutting solutions designed specifically for packaging processes, aiming to minimize downtime and support efficient production. The Strouse Corporation, American Industrial Company, and Gardico Inc each bring additional depth in custom parts, precision components, and long-standing service orientation across packaging and industrial applications.
At the same time, larger international players are shaping the broader market through scale, capital investment, and sustainability-focused innovation. DS Smith has moved aggressively into advanced rotary die-cutting capacity, including recent investment in high-precision corrugated board conversion. Mondi emphasizes die-cut carton and board solutions tied to sustainable packaging applications, while Smurfit Westrock continues to compete as a leading provider of die-cut boxes and cartons in corrugated and folding carton markets. Equipment and converting-technology suppliers also influence service capabilities indirectly by setting performance standards and enabling faster, more precise production. BOBST supports converting services and supplies advanced flatbed and rotary die-cutting equipment for folding carton and corrugated board packaging. MM Packaging specializes in die-cutting and creasing processes for cartonboard packaging to produce precise blanks for efficient forming.
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Providers are competing not only on price, but on process reliability, material breadth, sustainability alignment, and the ability to integrate die cutting into broader converting and packaging workflows.
Recent Developments Reshaping Market Dynamics
Recent corporate and technology developments underscore how quickly the operational baseline is changing. In March 2026, DS Smith invested DKK 100 million to install an advanced rotary die-cutting line with flexographic printing at its Grenaa facility in Denmark, increasing corrugated board capacity by up to 15 million square meters annually while improving precision on complex die cuts and reducing waste. This kind of investment signals the market's direction: higher throughput, better precision, and stronger emphasis on material efficiency.
In May 2025, Winkler+Dünnebier completed the acquisition of Sysco Machinery Corporation, adding advanced rotary die-cutting, slitting, and rewinding technologies for converting and packaging applications. The transaction illustrates how equipment and converting capability are being consolidated to strengthen integrated service offerings. In March 2025, BOBST launched the MASTERCUT 106 PER flatbed die-cutter at drupa 2025, showcasing 8,000 sheets per hour speed, quick-change capabilities, and a digital performance platform for folding carton and packaging production. Product launches like this expand the practical ceiling for conversion speed and flexibility, raising expectations for service providers who rely on or partner with equipment suppliers.
These developments matter because they affect more than individual companies. They shift customer expectations around lead times, precision, waste reduction, and integrated capability. They also influence the cost and risk profile of maintaining competitive service quality, especially for organizations that must meet increasingly demanding specifications without sacrificing throughput.
Raw Material Pressure and Regulatory Disruption
Market dynamics are not driven only by equipment and competition. Cost volatility and regulatory change are reshaping the operating environment at the same time. Recent pricing data shows continued pressure in corrugated and solid fiber box manufacturing inputs. The U.S. Producer Price Index for corrugated and solid fiber box manufacturing, specifically corrugated paperboard in sheets and rolls, reached 390.002 in March 2026. At the same time, corrugated paper prices in Northeast Asia were reported at 0.41 USD per kilogram in March 2026, compared with around 0.30 USD per kilogram in North America. These differences matter for sourcing strategy, margin planning, and regional service economics, especially for organizations exposed to cross-border supply chains or multi-site procurement.
On the regulatory side, packaging and paper product responsibility is advancing rapidly in the United States. Seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington, have enacted Extended Producer Responsibility laws for packaging and paper products, with ongoing implementation through 2026. In early 2026, Wisconsin and New Hampshire introduced EPR bills covering packaging, paper products, and beverage containers. Minnesota's packaging EPR framework requires producers to participate through a producer responsibility organization, with a needs assessment due by December 2026.
For die cutting service buyers and providers, these policies are not background noise. They influence material selection, waste-reduction priorities, reporting obligations, and the relative attractiveness of sustainable packaging formats. In practical terms, they can alter demand patterns for certain substrates, affect the cost of compliance, and reward service partners that can support material reduction, recyclability, or responsible sourcing claims with credible operational execution.
What the Full Report Delivers
The Worldwide Die Cutting Service Market research is designed to turn these forces into usable strategy. It combines market sizing and forecast context with segmentation analysis across process types, end-use industries, and regions. It profiles the competitive landscape and recent developments that are actively reshaping service capabilities. It also embeds the cost and regulatory environment into the analysis so that executives can evaluate not only where the market is heading, but what it will take to compete effectively within it.
Personal Electronic Die Cutting Market
Because this is a fast-moving market, the report is intended to support concrete decisions: how to structure supplier relationships, where to invest in process flexibility, how to anticipate compliance-driven material shifts, and how to position offerings in a fragmented but increasingly capability-sensitive market. The full dataset, segmentation detail, company profiles, and forward-looking scenario framing are available in the complete study.
Next Steps for Strategic Readers
If your organization is evaluating market entry, supplier consolidation, capacity expansion, or packaging and converting strategy for the 2026 to 2032 period, this research is built to inform those choices with rigor and commercial relevance. The executive summary and full market framework provide the level of detail required to move from general awareness to actionable intelligence. Readers seeking a complete view of segmentation splits, competitive positioning, regional dynamics, and the latest market developments are encouraged to access the full report through the source page, where the underlying data, profiles, and scenario context are presented in full.
For detailed analysis of this topic, please visit the official page: Worldwide Die Cutting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Civil Engineering Shape Memory Alloys Hit $245.5M in 2025, Growing 8.5% to $434.58M by 2032
By pmarketresearch, 2026-09-16
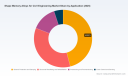
Unlocking the Future of Structural Resilience: A Strategic Overview of the Shape Memory Alloys in Civil Engineering Market 2026-2032
The global civil infrastructure landscape is undergoing a fundamental transformation. Driven by aging assets, increasing seismic risks, and the urgent demand for sustainable construction methodologies, engineers and investors are turning toward advanced material sciences to redefine structural integrity. At the forefront of this technological shift is the Shape Memory Alloys (SMA) sector. As we move further into 2026, the convergence of material innovation and structural engineering necessity presents a compelling investment thesis.
PW Consulting has released our comprehensive Worldwide Shape Memory Alloys for Civil Engineering Market research to provide stakeholders with the granular intelligence required to navigate this evolving terrain. This article serves as a strategic preview of the findings, highlighting the macro-economic trajectory, competitive dynamics, and technological catalysts that will define the market through 2032.
The Macro-Economic Trajectory: Growth Amidst Complexity
The expansion of the SMA civil engineering market is not merely incremental; it represents a structural recalibration of how infrastructure is built and maintained. Our analysis tracks revenue developments from 2020 through the forecast period ending in 2032. The historical data indicates a steady climb in market valuation, reflecting early adoption phases transitioning into broader commercial viability. Starting from a baseline in the mid-2020s, the market has demonstrated resilience despite global supply chain volatility.
Looking forward, the growth curve is projected to accelerate. The overall market size trajectory suggests a significant uplift in capital allocation toward SMA-integrated projects over the next decade. This growth is underpinned by a compound annual growth rate (CAGR) that signals robust demand penetration across multiple civil engineering verticals. For decision-makers, this implies that timing is critical. Entering the market or expanding existing portfolios now allows organizations to capture share during the steep ascent of the adoption curve. The revenue figures forecast for the late 2020s and early 2030s indicate a mature market phase where early movers will likely consolidate their technological lead.
However, growth is not uniform. It is mediated by material costs, regulatory frameworks, and geographical readiness. Understanding the interplay between these macro drivers and the specific revenue streams is essential for accurate budgeting and strategic planning.
Key Drivers Shaping the 2026 Landscape
Several converging factors are catalyzing demand for shape memory technologies in infrastructure. First, the imperative for seismic resilience is paramount. Traditional reinforcement methods are often heavy, labor-intensive, and reactive. SMAs offer superelastic properties that dissipate energy during seismic events, potentially reducing structural damage and lifecycle costs. This capability is shifting SMAs from experimental novelties to viable components in high-risk zones.
Shape Memory Alloys Market
Second, the focus on structural retrofitting and rehabilitation is intensifying. With vast networks of bridges and buildings reaching the end of their design lives, the industry requires solutions that can be deployed with minimal disruption to ongoing operations. SMA-based strengthening methods, particularly those involving iron-based alloys, offer advantages in terms of weight and corrosion resistance compared to traditional steel, facilitating easier installation and long-term durability.
Third, sustainability and efficiency are driving material innovation. The construction industry is under pressure to reduce carbon footprints. SMAs can contribute to lighter structures, reduced material usage, and extended service life. Furthermore, recent developments in digital fabrication and smart infrastructure integration are creating new use cases. For instance, the integration of SMA actuators in building technology for ventilation, shading, and fire protection systems represents an adjacent growth vector that complements core structural applications.
Finally, standardization is reducing market friction. The establishment of ASTM standards, including F2516 for shape memory alloys and related test methods, provides a framework for quality evaluation. This regulatory clarity supports procurement confidence and accelerates adoption among conservative engineering firms and government entities.
Competitive Dynamics and Vendor Landscape
The market structure is characterized by a mix of specialized material manufacturers and diversified engineering solution providers. Our research indicates a consolidated competitive environment where a core group of players holds a significant share of the revenue. The concentration ratio among the top firms highlights the technical barriers to entry and the importance of established supply chains and intellectual property.
Leading entities are not merely suppliers of raw materials; they are evolving into solution partners. Companies with vertically integrated operations, capable of managing the process from melting to component fabrication, are positioned to control quality and cost more effectively. For example, manufacturers specializing in nickel-titanium based alloys leverage high-performance properties for actuator and damping systems. Simultaneously, firms focusing on iron-based shape memory alloys are gaining traction for large-scale civil infrastructure elements due to advantages in mass production using conventional metallurgical equipment. This dual-track development suggests that the market will segment based on specific application requirements, with nickel-titanium dominating high-precision actuation and iron-based variants scaling for heavy structural strengthening.
Regional presence and application specialization further differentiate competitors. Some players have established strong footholds in structural strengthening and repair of concrete and masonry structures, including bridges, buildings, and silos. Others are integrating SMAs into building technology systems, offering full value chains from specification to assembly. Recent real-world applications demonstrate the transition from pilot projects to commercial deployment. Demonstrations of heat-activated strengthening methods for aging bridge decks and the use of memory-alloy steel in digitally fabricated concrete structures highlight the practical viability of these technologies.
Furthermore, collaborative research efforts are expanding the horizon. Upcoming international symposia focused on shape memory alloys in infrastructure are bringing together researchers and practitioners to discuss future directions. These knowledge exchanges are critical for aligning academic innovation with industrial application, ensuring that emerging technologies meet the rigorous demands of civil engineering practice.
For investors and procurement leaders, the key takeaway is that vendor selection must align with project-specific technical requirements. The optimal partner depends on whether the priority is high-performance actuation, cost-effective mass production for large elements, or integrated system solutions. The market offers diverse capabilities, but due diligence regarding supply chain stability and technical support is essential.
Strategic Implications for Stakeholders
The findings of this report have direct implications for various stakeholders in the construction and infrastructure ecosystem.
- Infrastructure Owners and Operators: Understanding the lifecycle cost benefits of SMA integration is crucial. While initial material costs may be higher, the potential for reduced maintenance, enhanced seismic performance, and extended service life can yield favorable total cost of ownership outcomes. Strategic planning should consider pilot projects in critical assets where performance gains justify material premiums.
- Engineering Firms: Incorporating SMA technologies into design capabilities can differentiate service offerings. Firms that master the specification, detailing, and construction methods for SMA applications will be well-positioned to lead projects that demand advanced resilience features. Continuous training and knowledge acquisition regarding standards and best practices are recommended.
- Material Suppliers and Manufacturers: The projected growth trajectory supports capacity expansion and R&D investment. However, attention to raw material volatility is necessary. Feedstocks such as nickel and titanium are subject to price fluctuations influenced by mining restrictions and geopolitical factors. Developing robust supply chain strategies and exploring alternative alloy formulations, such as iron-based variants, can mitigate exposure.
- Investors: The market shows promise, but due diligence is required. Focusing on companies with proven application records, vertical integration, and strong IP positions offers a pathway to capturing value. Monitoring the evolution of regional demand and regulatory support can provide leading indicators of market shifts.
The Value of PW Consulting's Deep Dive
While the trends outlined above provide the strategic context, execution requires precision. Market growth rates, competitive positioning, and application-specific revenue streams vary significantly across regions and segments. Generalizations can obscure the specific opportunities and risks relevant to your organization.
PW Consulting's Worldwide Shape Memory Alloys for Civil Engineering Market report offers the depth required to move from strategy to action. The report provides a detailed segmentation analysis, examining the market through lenses such as alloy type, application focus, and geography. It includes granular data on demand drivers, restraints, and opportunities that enable accurate forecasting and scenario planning.
Moreover, the competitive analysis goes beyond company profiles. It evaluates market share dynamics, strategic moves, and the implications of recent developments, such as new strengthening methods and symposia that shape industry consensus. The report also contextualizes regulatory environments, including the impact of standards and material availability, helping stakeholders anticipate compliance costs and supply constraints.
Worldwide Shape Memory Alloys for Civil Engineering Market
Readers interested in leveraging this intelligence for their 2026 decision-making are encouraged to access the full report. The detailed data tables, segmentation splits, and competitive assessments contained within the document provide the granularity necessary to refine market entry strategies, optimize procurement negotiations, and identify high-potential niches. Access to the complete analysis ensures that your strategic initiatives are built on a foundation of verified, up-to-date market intelligence.
Conclusion
The intersection of advanced materials and civil engineering is creating a new paradigm for infrastructure resilience. Shape memory alloys are moving from the laboratory to the construction site, driven by seismic needs, aging infrastructure, and the pursuit of efficiency. The market outlook through 2032 indicates substantial growth, supported by technological maturation and increasing standardization.
As the industry navigates this transition, informed decision-making will be the differentiator between leaders and laggards. PW Consulting remains committed to providing the analytical rigor and strategic insight necessary to thrive in this dynamic environment. The full market study offers the detailed roadmap required to capitalize on the opportunities presented by the evolving shape memory alloys landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MLCC Dielectric Materials Market Hits $1.86 Billion in 2025, Growing at 7.05% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Future of Electronic Performance: The Strategic Imperative of the Global MLCC Dielectric Materials Market
For procurement leaders, R&D directors, and corporate strategists operating in the electronics value chain, the materials that enable miniaturization and reliability are no longer a back-office concern. They are a front-line competitive differentiator. As multilayer ceramic capacitors (MLCCs) continue to anchor everything from 5G infrastructure and electric vehicles to medical implants and aerospace systems, the underlying dielectric materials that dictate capacitance density, stability, and thermal resilience have become the nucleus of supply chain resilience and product differentiation. Our newly released Worldwide MLCC Dielectric Materials Market research delivers a comprehensive, data-backed roadmap for organizations that must align material sourcing, product roadmaps, and capacity investments with the trajectory of a rapidly evolving landscape.
The global market for MLCC dielectric materials has demonstrated remarkable resilience and structural growth over the past half-decade. Valued at approximately 1,856.40 million USD in the base year of 2025, the sector has navigated cyclical demand fluctuations, raw material volatility, and shifting end-market appetites to sustain a robust compound annual growth rate of 7.05 percent through the forecast horizon extending to 2032. This trajectory underscores a fundamental reality: the demand for advanced dielectric formulations is not merely cyclical but structurally embedded in the electrification of transportation, the densification of consumer electronics, and the proliferation of high-frequency communication networks. For decision-makers, understanding where this growth concentrates, which material architectures are gaining share, and how legacy supply chains are adapting is the difference between reacting to market shifts and shaping them.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle arrives at a critical inflection point. Supply chain architects are recalibrating tier-two and tier-three supplier dependencies in the wake of geopolitical realignment and regional manufacturing incentives. Simultaneously, product developers are pushing capacitance targets higher while shrinking form factors to the limits of ceramic processing science. The dielectric material layer sits precisely at the intersection of these pressures.
Our forecast model maps a clear acceleration pathway for the sector, with revenue projections climbing from 1,923.77 million USD in 2026 toward 2,980.98 million USD by 2032. More importantly, the analysis isolates the inflection triggers that will separate transient demand spikes from durable structural shifts. By synthesizing historical pricing behavior, capacity commissioning timelines, and application-driven material specification trends, the report equips strategists with a decision framework that extends well beyond headline growth figures. Whether you are evaluating vertical integration opportunities, assessing supplier qualification pipelines, or modeling the cost implications of next-generation dielectric formulations, this research converts macro trends into actionable intelligence.
Market Architecture: Materials, Classes, and the Forces Shaping Demand
The composition of the MLCC dielectric market reflects decades of materials engineering evolution, yet its present structure is being rewritten by application requirements that demand simultaneously higher performance and lower environmental impact. Barium titanate remains the foundational dielectric compound for both Class I and Class II capacitors, enabling high capacitance density within ultra-thin ceramic layers. However, the market segmentation reveals a nuanced hierarchy of material technologies, each serving distinct performance envelopes and end-use priorities.
- High Purity Barium Titanate continues to dominate as the primary dielectric material, driven by its proven balance of permittivity, manufacturability, and compatibility with high-volume multilayer processing. Japanese suppliers in particular have advanced hydrothermal synthesis routes to deliver grades optimized for precision capacitance stability and ultra-fine grain structures.
- Zirconates and Stannates occupy a strategic niche, offering tailored electrical and mechanical properties that complement barium titanate-based systems in specialized high-reliability and high-voltage applications.
- Rare Earth Doping Oxides represent a more specialized formulation pathway, supporting capacitance tuning and temperature stability for applications where marginal gains in dielectric performance translate into meaningful system-level advantages.
Equally important is the division between dielectric classes, which directly informs material selection and supplier strategy:
- Class II formulations, encompassing X7R, X5R, and Y5V characteristics, command the largest share of material demand due to their prevalence in consumer electronics, automotive electronics, and power management circuits where high volumetric efficiency is paramount.
- Class I materials, including C0G and NP0 types, serve applications demanding exceptional temperature stability, low loss, and long-term reliability, making them indispensable for RF front-ends, precision timing circuits, medical devices, and defense-grade systems.
The market is also defined by notable concentration dynamics. With the top three players commanding 62.45 percent of market share and the top five reaching 78.9 percent, the competitive landscape reflects a mature, technology-intensive ecosystem where formulation expertise, process control, and customer qualification cycles create formidable barriers to entry. For buyers and investors alike, this concentration signals both supply assurance risks and the strategic value of locking in qualified supplier relationships before capacity tightens.
Competitive Landscape: Incumbents, Integrators, and Enabling Material Specialists
The companies profiled in this research illustrate the full spectrum of the dielectric value chain, from powder synthesis and formulated material supply to finished capacitor manufacturing and high-reliability application specialization. Understanding who competes where, and how their material capabilities differentiate their product portfolios, is essential for mapping partnership opportunities and evaluating substitution threats.
Among the leading integrated capacitor manufacturers, Murata Manufacturing Co., Ltd. continues to leverage advanced in-house dielectric material formulations, with recent emphasis on high-capacitance X7R architectures and ultra-miniature dielectric layers that support consumer electronics, automotive, and high-reliability applications. Murata’s July 2025 commencement of mass production for 0402-inch high-capacitance MLCCs at 47 µF, enabled by upgraded dielectric layering technology, exemplifies the pace at which formulation and process innovation are compressing performance boundaries.
Samsung Electro-Mechanics Co., Ltd. maintains a prominent position through proprietary dielectric materials optimized for high capacitance, automotive-grade reliability, and miniaturized components deployed across smartphones, electric vehicles, and 5G infrastructure. TDK Corporation remains a defining force in advanced fine-particle dielectric technologies, with recent moves including the expansion of its CN series to deliver low-resistance soft-termination MLCCs in the 3225 case size, offering 22 nF capacitance and C0G characteristics at 1000 V. TDK’s September 2024 automotive lineup expansion further underscored its focus on industry-leading capacitance at 100 V in 2012 and 3216 sizes, alongside new low-resistance soft termination types built on advanced dielectric formulations.
Yageo Corporation, through its broader portfolio including KEMET and AVX, supplies MLCCs anchored in barium titanate-based dielectrics with emphasis on high-voltage, automotive, and high-reliability segments. Taiyo Yuden Co., Ltd. specializes in high-performance MLCCs with customized dielectric materials spanning automotive, industrial, and consumer electronics use cases. Kyocera Corporation, including its AVX subsidiary, continues to manufacture high-reliability MLCCs using advanced ceramic dielectric formulations targeted at automotive, medical, and aerospace sectors, while Walsin Technology Corporation provides MLCCs incorporating dielectric materials tailored for both general-purpose and specialized electronic applications.
Worldwide MLCC Dielectric Materials Market
On the materials supply side, the competitive dynamics shift toward companies whose core competency lies in dielectric powder engineering and formulation technology. Knowles Precision Devices focuses on high-reliability and high-performance MLCCs with specialized dielectric formulations for medical, military, and 5G markets. Prosperity Dielectrics Co., Ltd. supplies ceramic dielectric powders and formulations across PME and BME series for NP0, X7R, and Y5V applications, directly feeding MLCC production pipelines. Vibrantz Technologies provides engineered dielectric powders and formulated materials for multilayer ceramic components, including both Class I C0G-type and Class 2 X7R-type materials. Sakai Chemical Industry Co., Ltd. has established itself as a key supplier of high-purity barium titanate dielectric powders produced via hydrothermal synthesis for premium MLCC applications, while Nippon Chemical Industrial Co., Ltd., Fuji Titanium Industry Co., Ltd., and Toho Titanium Co., Ltd. round out a robust Japanese supply base producing barium titanate and titanium-based materials critical to electronic dielectric applications.
This interplay between integrated capacitor makers and specialized dielectric material suppliers creates a layered competitive field. For strategists, the implication is clear: material sourcing decisions cannot be made in isolation from the product architecture strategies of the companies that consume them, and vice versa.
Multilayer Ceramic Capacitors (MLCCs) Market
Technology, Regulation, and Supply Chain Dynamics Reshaping the Market
The trajectory of the MLCC dielectric materials market is being shaped not only by performance demands but also by environmental compliance and raw material processing strategies. Manufacturers across the value chain continue to advance lead-free and RoHS-compliant dielectric formulations to meet global environmental standards. This regulatory momentum is not merely a compliance exercise; it is reshaping formulation roadmaps, supplier qualification timelines, and long-term cost structures. Organizations that treat regulatory adaptation as a strategic variable rather than a procedural checkbox will secure advantages in time-to-market and supply continuity.
Raw material dynamics further reinforce the need for strategic foresight. Barium titanate remains the workhorse dielectric for both Class I and Class II capacitors, and the availability of high-purity grades produced through controlled synthesis routes directly influences capacitance consistency, mechanical integrity, and yield performance. Suppliers that have invested in advanced powder processing and particle size control are positioning themselves to serve the most demanding applications, while downstream manufacturers increasingly prioritize qualification partnerships that guarantee batch-to-batch reproducibility. As electrification, connectivity, and miniaturization drive demand toward tighter tolerances, the quality of the dielectric material input becomes a direct determinant of end-product performance and warranty risk.
What the Research Delivers: An Operational Blueprint for Decision-Makers
This report is designed to move beyond descriptive market summaries and into the operational detail that strategic teams require. It integrates historical analysis from 2020 through 2025 with a forward-looking forecast spanning 2026 to 2032, enabling readers to benchmark current positioning against projected growth corridors and identify where capacity, formulation, and qualification investments will yield the greatest returns.
Within the analysis, readers will find:
- A structured assessment of material type segmentation, clarifying how barium titanate-based systems, zirconates and stannates, and rare earth doping oxides each contribute to revenue composition and where application pull is accelerating adoption.
- A detailed evaluation of dielectric class dynamics between Class II and Class I materials, including the performance-driven demand patterns that influence formulation priorities and supplier selection.
- A competitive profiling framework covering leading integrated manufacturers and specialized dielectric material suppliers, with attention to geographic footprints, technological positioning, and recent product and capacity developments.
- Contextual analysis of industry dynamics, including raw material sourcing considerations, formulation trends, and regulatory drivers that influence cost structures and supply chain design.
- Forecast scenarios and market sizing that translate top-line growth into interpretable guidance for capacity planning, sourcing strategy, and investment prioritization.
Crucially, the full report provides the granular segmentation detail, regional revenue distributions, and application-level breakdowns that executive summaries cannot accommodate. These deeper layers enable teams to model localized supply-demand balance, evaluate supplier concentration risk within specific material categories, and align product roadmap milestones with realistic material availability timelines.
Strategic Takeaways for 2026 and Beyond
The Worldwide MLCC Dielectric Materials Market research is built for leaders who need to convert complex material science trends into executable strategy. It frames the market not as a static size estimate but as a dynamic system in which formulation capability, regulatory adaptation, regional manufacturing footprints, and application-driven performance requirements continuously reshape competitive advantage.
In practical terms, the insights contained in this study support several priority actions for 2026 planning:
- Evaluate supplier qualification pipelines against material class requirements, distinguishing between high-volume Class II needs and stability-critical Class I demands.
- Assess the strategic implications of market concentration, particularly where top-tier suppliers hold disproportionate influence over qualified material supply and lead times.
- Integrate environmental compliance and lead-free formulation roadmaps into sourcing decisions, recognizing that regulatory momentum will affect cost, availability, and qualification cycles.
- Align internal R&D and procurement roadmaps with the material technologies most likely to support next-generation capacitance density, miniaturization, and high-reliability performance targets.
The full intelligence behind these recommendations, including the segment-level data, regional breakdowns, and detailed company assessments that enable precise planning, is available in the complete report. For organizations ready to move from general market awareness to targeted, evidence-based decision-making, the complete Worldwide MLCC Dielectric Materials Market research provides the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Briquettes Hit $925.4M in 2025, Projected to Surge to $1,520M by 2032
By pmarketresearch, 2026-09-16
Global Wood Briquettes Market: Strategic Intelligence for 2026 Investment and Operational Planning
Executive Overview of Market Trajectory
The Worldwide Wood Briquettes Market represents a critical intersection of renewable energy policy, industrial decarbonization, and residential heating demand. As organizations navigate the complex energy transition landscape, understanding the quantitative and qualitative dimensions of this sector is paramount for strategic positioning. This market research study provides a comprehensive analysis of market size, growth trajectories, and competitive forces shaping the industry through the forecast period ending in 2032.
Having attained a valuation of approximately 925 million USD in the base year of 2025, the market has demonstrated consistent resilience. Historical data from 2020 through 2025 illustrates a steady accumulation of value, reflecting both organic growth and increased adoption rates across diverse geographical zones. Looking forward, the market is projected to reach 997.6 million USD in 2026, marking a significant step in its expansion curve. This growth is not merely linear but compounds over time, driven by entrenched policy frameworks and shifting consumer preferences toward sustainable biomass solutions. The compound annual growth rate is estimated at 7.35 percent during the forecast period, indicating a robust opportunity for stakeholders who can align their operations with emerging demand patterns.
To fully capitalize on this momentum, decision-makers require more than aggregate figures. They need granular intelligence on segment performance, regional divergences, and the specific regulatory headwinds or tailwinds that will define profitability in the coming years. This report is designed to bridge that gap, offering an evidence-based roadmap for navigating the wood briquettes value chain.
Core Segmentation and Structural Dynamics
Product Type and Material Inputs
The market structure is defined by distinct product categories that cater to varying combustion requirements and feedstock availability. Analysis within this study differentiates between sawdust-based formulations, agro-waste derivatives, and wood residue or chip-based briquettes. Each type possesses unique characteristics regarding energy density, ash content, and production economics. Sawdust briquettes often dominate in terms of volume due to their prevalence in processing streams, while agro-waste variants present opportunities in regions where agricultural biomass is abundant. Wood residue and chips briquettes serve specialized industrial applications where specific burning characteristics are required.
Understanding the cost implications of raw material sourcing is critical. For instance, sawmill residues and wood chips for briquette production have shown price volatility in key markets, with averages in the EU reaching specific levels during late 2023. These input costs directly affect margin structures and pricing strategies. The report delves into how manufacturers mitigate these fluctuations through supply chain optimization and long-term contracting, ensuring that production remains viable even when feedstock prices fluctuate.
Application Segments and Demand Centers
Demand is distributed across several key application verticals, each with distinct growth drivers. Industrial boilers represent a significant portion of consumption, driven by large-scale manufacturing entities seeking cost-effective and compliant heating solutions. Residential heating remains a cornerstone of the market, fueled by consumer desire for carbon-neutral heating options and the aesthetic value of wood-burning stoves. Power generation applications are gaining traction as utilities seek to diversify energy portfolios with biomass feedstocks. Commercial and other applications round out the demand landscape, encompassing hospitality, education, and municipal heating projects.
The interaction between these application segments and regional policies creates a complex web of opportunity. In some jurisdictions, subsidies for biomass boilers significantly enhance residential adoption rates, while in others, industrial regulations mandate specific emission savings that favor high-quality briquettes over raw wood. This study dissects these application-led demand vectors to identify where volume growth is most concentrated and where margin profiles are most favorable.
Regional Market Architecture
Geographically, the market exhibits pronounced differences in maturity, demand volume, and growth speed. Europe currently holds a substantial share of the global market, supported by stringent carbon reduction targets and established biomass infrastructure. Asia Pacific follows as a significant region, characterized by rapid industrialization and increasing awareness of renewable energy alternatives. North America maintains a steady presence, driven by residential heating trends and industrial usage. Latin America and the Middle East and Africa represent emerging territories where market penetration is still developing but holds latent potential.
Regional analysis in this report goes beyond simple revenue allocation. It examines the regulatory environments, logistical constraints, and competitive intensities specific to each zone. For example, the European landscape is heavily influenced by directives such as RED III, which requires solid biomass to meet minimum greenhouse gas emission savings compared to fossil fuels. Such regulations shape not only demand but also the types of products that can be legally sold and subsidized. Similarly, the UK Boiler Upgrade Scheme provides financial incentives for biomass boiler installations, directly stimulating downstream demand in that region. Understanding these regional nuances is essential for any firm planning cross-border expansion or supply chain adjustments.
Competitive Landscape and Strategic Positioning
Key Enterprise Profiles and Operational Focus
The competitive arena is populated by a mix of established manufacturers and specialized producers, each carving out niches based on product quality, geographic reach, and operational scale. Prominent players include Lignetics International, headquartered in Louisville, Colorado, which manufactures premium wood briquettes and compressed logs for residential heating, BBQ, and commercial fireplaces. Their focus on consumer-facing quality highlights one end of the market spectrum.
In Europe, Binderholz GmbH, based in Sankt Johann in Tirol, Austria, produces high-quality wood briquettes from sawmill residues for sustainable heating solutions. Their operations are closely tied to regional milling capacity and EU demand trends. Pfeifer Group, located in Imst, Austria, offers RUF-type wood briquettes as part of its broader range of renewable wood energy products for industrial and residential use, demonstrating the integration of briquette production within larger timber and energy portfolios.
German manufacturers also play a pivotal role. Holzindustrie Torgau GmbH & Co. KG, based in Torgau, specializes in manufacturing pressed wood briquettes certified under DINplus for efficient biomass heating. Südruss Holz GmbH, situated in Unterkirnach, produces natural wood briquettes without additives for export and domestic heating markets, emphasizing purity and export capability. In North America, Bear Mountain Forest Products, located in Eagle River, Wisconsin, supplies dense hardwood briquettes designed for long-burning residential stoves and fireplaces, catering to the premium residential segment.
On the global export front, Jay Khodiyar Industries, headquartered in Rajkot, Gujarat, India, exports 100 percent wood briquettes and biomass variants to global markets for industrial boilers and heating. This company exemplifies the growing role of Asian producers in supplying international markets, leveraging cost advantages and robust manufacturing capabilities.
Strategic Developments and Market Moves
Recent developments among these key entities reveal the strategic priorities shaping the industry. In June 2024, Binderholz GmbH announced an expansion of wood briquette production capacity at its Austrian facilities to meet rising EU demand. This move underscores the confidence major players have in the growth trajectory of the European market and their willingness to invest in capacity when regulatory and demand signals are positive.
Earlier, in November 2023, Holzindustrie Torgau achieved updated DINplus certification for a new briquette product line. Certifications such as DINplus are critical in the wood briquettes market, as they signal compliance with rigorous standards regarding ash content, fines, and overall combustion performance. DIN 51731, for instance, mandates a maximum of 10 percent ash content and 0.5 percent fines for premium wood briquettes. Achieving and maintaining such certifications is a barrier to entry and a competitive differentiator, allowing firms to command premium pricing, such as the levels observed in Central Europe during the 2024 heating season where ENplus A1 wood briquettes retailed at specific price points per tonne.
The market concentration remains relatively fragmented, with top three players holding approximately 18.45 percent of revenue and the top five holding about 26.32 percent. This fragmentation suggests that while leading brands have strong positions, there is ample room for consolidation, niche specialization, or regional dominance strategies.
Regulatory, Standardization, and Economic Drivers
Policy Frameworks and Emission Requirements
Regulatory environments are among the most powerful drivers in the wood briquettes market. In the European Union, the RED III directive requires solid biomass like wood briquettes to meet greenhouse gas emission savings of at least 70 percent versus fossil fuels. This mandate forces both producers and consumers to ensure that biomass products are sourced and processed in ways that demonstrably reduce carbon footprints. It influences everything from feedstock selection to logistics and end-use verification.
Beyond emission targets, subsidy Schemes play a direct role in stimulating demand. The UK Boiler Upgrade Scheme, for instance, provides up to £7,500 grants for biomass boilers compatible with wood briquettes. Such financial mechanisms lower the capital barrier for end-users, accelerating the transition from fossil-fuel heating to biomass systems. The interplay between subsidies, certification standards, and carbon targets creates a multi-layered incentive structure that the report analyzes in detail to help stakeholders predict policy-driven demand shifts.
Quality Standards and Pricing Dynamics
Product quality is not merely a marketing claim; it is a regulatory and commercial necessity. Standards like DIN 51731 set benchmarks that protect consumers and ensure efficient combustion, reducing maintenance issues and emissions. Market data indicates that premium certified briquettes command specific price premiums in key markets. For example, during the 2024 heating season, ENplus A1 wood briquettes achieved retail prices in a defined range per tonne in Central Europe. These pricing dynamics reflect the value that consumers and industrial buyers place on reliability, consistency, and compliance.
Manufacturers must navigate the tension between production costs, which are sensitive to raw material prices and energy inputs, and the price ceilings imposed by market acceptance and competitive pressure. The report provides a framework for analyzing how shifts in input costs, such as the average European price for sawmill residues and wood chips, translate into margin impacts and pricing strategies across different product types and application segments.
Strategic Value of This Market Research Study
Comprehensive Data Coverage and Forecasting Rigor
This study is constructed to provide actionable intelligence for strategic planning. It covers historical data from 2020 through 2025, offering a robust baseline for trend analysis, and extends forecasts through 2032. The projection period allows organizations to stress-test their strategies against multiple growth scenarios and to align capital expenditure cycles with anticipated market expansion.
The report integrates quantitative forecasts with qualitative assessments of the factors driving those numbers. Rather than presenting isolated figures, the analysis contextualizes market size and growth rates within the broader ecosystem of feedstock availability, regulatory requirements, technological advancements in briquetting, and shifting consumer preferences. This holistic approach ensures that the data is interpretable and applicable to real-world decision-making.
Briquette Market
Segmentation Analysis for Targeted Strategy
One of the core strengths of this research is its detailed segmentation framework. By breaking down the market by region, type, and application, the study enables stakeholders to identify their most relevant growth pockets. A manufacturer focused on premium residential products can assess the health and growth potential of the residential heating segment across key regions. An industrial supplier can evaluate the demand outlook for industrial boilers and power generation applications. This granularity supports targeted marketing, production planning, and distribution strategies.
It is important to note that while this article highlights the breadth and depth of the analysis available, the full report contains the precise quantitative allocations and detailed forecasts for each segment and region. These specifics are essential for building financial models, setting sales targets, and evaluating investment returns with precision. Readers seeking the complete segment-level data, including exact historical and projected revenue breakdowns, are encouraged to access the full report through the source webpage.
Competitive Intelligence and Strategic Benchmarking
Understanding the competitive landscape is vital for positioning. This study profiles key companies, analyzing their strategic moves, product focus, geographic presence, and recent developments. By examining events such as capacity expansions, certification achievements, and export initiatives, the report helps firms benchmark their own strategies against industry leaders. It also sheds light on the nature of competition in a fragmented market, highlighting where consolidation is likely and where niche players can thrive.
The inclusion of recent developments, such as the capacity expansion by Binderholz and the certification update by Holzindustrie Torgau, provides timely insights into the operational priorities of major actors. These case examples, combined with broader competitive metrics, offer a practical view of how firms are responding to market opportunities and regulatory demands. For organizations evaluating partnership opportunities, acquisition targets, or competitive threats, this intelligence is invaluable.
Operational and Investment Decision Support
Ultimately, the purpose of this market research is to reduce uncertainty and improve the quality of strategic decisions. For investors, the report provides the data needed to assess market attractiveness, growth sustainability, and risk factors. For manufacturers and suppliers, it offers insights into demand trends, pricing environments, and competitive pressures that inform production planning, capacity investment, and product development. For policymakers and industry associations, it contributes to a clearer understanding of market dynamics and the impact of regulatory measures.
Worldwide Wood Briquettes Market
The study is designed to be a living reference that supports ongoing strategic dialogue. As the market evolves, with changes in feedstock markets, regulatory updates, and technological innovations, the framework provided by this research helps stakeholders adapt and respond proactively. The forecast period through 2032 offers a long enough horizon to plan for structural shifts while remaining specific enough to guide near-term actions in 2026 and beyond.
Detailed data tables, segment-specific growth rates, regional revenue projections, and comprehensive company profiles are available in the full downloadable report. Accessing these resources will enable your organization to conduct a thorough internal analysis and develop strategies that are precisely calibrated to the opportunities and challenges of the Worldwide Wood Briquettes Market.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com